Agentic Commerce · October 11, 2026
Accelerating FinTech Innovation in Britain: How Torly.ai Validates Agentic Payment Startups
Learn how Torly.ai enables pioneering FinTech founders to articulate viable, scalable agentic commerce solutions that satisfy strict UK endorsing body criteria.
The Rise of Machine Buyers: Why UK Endorsing Bodies Demand Real Proof
Autonomous software agents are no longer just answering support tickets or writing drafts. Today, they are researching products, comparing rates, and completing transactions from start to finish without human intervention. Global payments giants are racing to build rails for this shift, linking transaction networks with autonomous digital wallets. If you are an international founder building in this space, Britain is arguably the best testing ground in the world. Yet, convincing a Home Office endorsing body that your autonomous finance concept is viable takes far more than clever code. It requires robust validation, regulatory alignment, and cutting-edge AI Driven Visa Intelligence to turn technical ambition into an indisputable business case.
Navigating the UK Innovator Founder Visa route means proving three strict criteria: innovation, viability, and scalability. Many technical founders stumble here. They pitch complex autonomous algorithms, but endorsing bodies look for commercial defensibility, compliance frameworks, and credible financial projections. Without an objective framework to stress-test your proposal against official benchmarks, great ideas get rejected daily. Bridging the gap between bleeding-edge machine transactions and rigid immigration compliance is now the defining challenge for overseas entrepreneurs.
What Agentic Commerce Actually Means for FinTech Founders
We have moved past simple automation. Traditional e-commerce relies on human clicks, manual form fills, and one-time two-factor authentication prompts. Agentic commerce flips this model completely.
In an agentic ecosystem, an artificial intelligence agent acts as a delegated buyer. The agent evaluates thousands of merchant options, balances preferences, negotiates micropayments, and authorises funds autonomously. Major card schemes and enterprise merchant processors are already establishing tokenised identity standards to handle machine-to-machine checkout securely.
For a startup founder, this shift introduces complex operational hurdles:
- Authorisation protocols: How does an AI prove consumer intent without triggering instant fraud flags?
- Dispute mechanisms: What happens when an autonomous agent orders the wrong enterprise software tier?
- Liquidity management: How do automated wallets settle cross-border balances in real time?
When presenting these models to UK endorsing bodies, hand-waving will not work. Evaluators are seasoned commercial professionals. If you cannot articulate your fraud mitigation architecture or your path to enterprise distribution, your application will stall. You can test your core assumptions and Build your Business Plan NOW before submitting raw technical notes to external assessors.
The Triad of Endorsement: Innovation, Viability, Scalability
The Home Office requires endorsing bodies to filter for genuine originality and economic benefit to the United Kingdom. Let us break down how an autonomous payment startup must satisfy each pillar.
1. True Innovation
You cannot merely resell existing payment gateways or wrap a basic chatbot around an API. Innovation requires genuine intellectual property or a radically novel delivery model. In agentic commerce, this could mean proprietary risk scoring for autonomous transactions, novel cryptographic signature schemes, or dynamic escrow systems built specifically for automated software bots.
2. Commercial Viability
Can your business survive in the wild? Endorsing bodies want clear proof of market demand, detailed cash-flow projections, and realistic capital expenditure models. You must show that your unit economics make sense once cloud compute, transaction fees, and regulatory audits are factored into every ledger entry.
3. Sustainable Scalability
Scalability means creating high-skilled UK jobs and expanding into international territories. For an AI FinTech startup, you must show how your platform scales its gross merchandise value without requiring linear headcount growth. Demonstrating customer acquisition funnels, clear partner channels, and international regulatory readiness is mandatory.
Why Traditional Visa Consultancy Falls Short for Deep-Tech
The UK visa consultancy sector is a multi-billion-pound market, but it was largely built for traditional trading companies, retail businesses, and consultancies. Deep-tech startups present a unique challenge that generic advisors struggle to navigate.
Most immigration lawyers understand the Immigration Rules thoroughly, yet they rarely understand how tokenised machine credentials or autonomous checkout pipelines function. Conversely, standard business plan writers often use generic templates that fail to address the specific evaluation rubrics used by official endorsing bodies. The result? Founders receive generic, bloated documents that misrepresent their technical edge and fail basic viability checks.
This disconnect is why data-driven evaluation has become essential. Advanced AI systems can evaluate technical startups with the depth of a seasoned venture partner and the precision of an immigration specialist. By applying dedicated algorithmic assessment, founders can instantly identify logical gaps in their commercial models, identify compliance weaknesses, and refine their submissions efficiently. To ensure your tech stack and operational plans align with strict UK immigration standards, leverage AI-Powered UK Innovator Visa Application Assistant to audit your readiness.
How Torly.ai Deconstructs and Validates FinTech Ventures
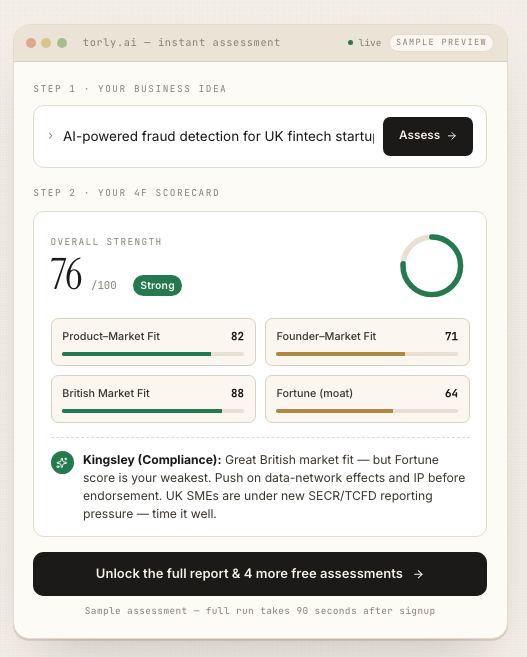
Torly.ai operates as an intelligent visa readiness platform built specifically to eliminate guesswork for global entrepreneurs. Rather than treating your application as a simple paperwork exercise, the platform uses dedicated reasoning agents to stress-test your business against actual endorsing body criteria.
Here is how the platform evaluates an autonomous FinTech startup:
- Idea Qualification: The platform runs multi-layered evaluations to verify if your agentic payment protocol satisfies official innovation and market disruption tests.
- Background Analysis: Your technical capabilities, commercial achievements, and leadership history are mapped against the specific founder profile endorsing bodies look for.
- Gap Identification and Strategy: The system pinpoints exact weaknesses in your customer acquisition cost, team structure, or compliance roadmap, giving you concrete steps to resolve them.
- Dynamic Scoring: The evaluation updates continuously based on changing policy guidance and recent endorsement trends across UK enterprise hubs.
Instead of spending weeks waiting for manual reviews from external advisors, founders get actionable feedback in real time. If you want to streamline the documentation phase completely, the TorlyAI Desktop APP lets you manage your submission materials directly from your workstation with dedicated local workflows.
Transforming Machine Payments into an Endorsement-Ready Roadmap
Let us examine how a hypothetical agentic FinTech startup refines its proposal for UK endorsement.
Imagine an entrepreneur developing an autonomous purchasing protocol for procurement teams. The software allows software agents to negotiate volume discounts with cloud vendors and settle payments automatically.
To bridge this gap successfully, you must structure your pitch around clear commercial pillars:
- Regulatory Navigation: Explain how your autonomous payment layer interacts with Financial Conduct Authority (FCA) permissions, anti-money laundering (AML) controls, and customer verification rules.
- Pilot Validation: Document letters of intent, pilot agreements, or enterprise sandbox tests that prove real-world demand in the British market.
- Financial Resilience: Outline clear three-year profit and loss forecasts that account for payment processing interchange fees, chargeback reserves, and technical infrastructure overheads.
Refining these detailed sections manually can take hundreds of hours of drafting and recalculation. You can accelerate this entire journey and Build Your Endorsement Application with 6 AI Agents designed to handle business modelling, market sizing, and compliance cross-checks systematically.
Britain as the Global Launchpad for Agentic Commerce
The UK remains Europe’s undisputed FinTech capital. Between the regulatory sandbox initiatives run by the FCA, deep venture capital networks in London, and world-class academic research in Cambridge and Oxford, Britain provides the ideal environment for autonomous payment platforms.
Moreover, British consumers and enterprises show some of the highest digital payment adoption rates in the world. As global financial giants establish new rails for machine-initiated commerce, the startups that build the security, routing, and identity layers will capture enormous market share. Securing an Innovator Founder Visa grants you a direct path to permanent residency, giving you the operational freedom to scale without investor-restrictive visa ties.
By pairing your engineering expertise with data-driven evaluation tools, you eliminate administrative friction, sidestep common rejection pitfalls, and present a bulletproof commercial case to endorsing bodies.
Take control of your UK expansion today by securing your foundational validation through AI Driven Visa Intelligence, and build the future of autonomous commerce on British soil.