Agentic Commerce · October 11, 2026
AI-Powered UK Innovator Visa Application Assistant: Capitalising on Agentic Commerce and AI Payment Innovation
Discover how AI-Powered UK Innovator Visa Application Assistant helps fintech founders transform agentic commerce innovations into endorsement-ready UK business plans.
The Autonomous Revolution: Why Agentic Commerce Demands Next-Level Visa Intelligence
Software agents are no longer just summarising PDFs or writing snippets of Python. In fintech, autonomous AI agents are now negotiating deals, subscribing to cloud services, and completing programmatic fiat transactions via automated cards on traditional payment rails. When developer platforms connect artificial intelligence straight into card networks, you realise that the machine-to-machine economy has arrived. If you are a global founder building in this agentic commerce space, the United Kingdom represents one of the most lucrative hubs in the world. Yet, pitching a machine-to-merchant startup to an endorsing body requires more than technical code; it demands rigorous validation through modern AI Driven Visa Intelligence.
The UK Innovator Founder Visa route wants genuine innovation, commercial viability, and global scalability. However, bridging the gap between autonomous financial infrastructure and strict Home Office criteria can feel like speaking two incompatible languages. Endorsing bodies do not care about raw jargon; they care about verifiable compliance, clear market moats, and realistic growth forecasts. To navigate this barrier, forward-thinking founders are using specialised platforms to validate their business ideas, assess applicant suitability, and map out watertight business plans before submitting an endorsement application.
The Rise of Agentic Commerce: How AI Agents Are Getting Their Own Wallets
For decades, digital commerce relied entirely on human intent. You clicked a button, entered your card details, passed two-factor authentication, and completed the order. Today, the script has flipped. Agentic commerce introduces autonomous software agents capable of executing multi-step business decisions without human intervention.
Think about the operational mechanics here:
* Autonomous resource balancing: An AI agent senses a surge in compute demand and instantly provisions more private server instances.
* Micro-procurement: Software agents buy real-time data feeds, pay per API call, or hire other agents for discrete computational tasks.
* Smart cash flow: Programmable bots pay bills and collect micro-invoices using virtual debit infrastructure.
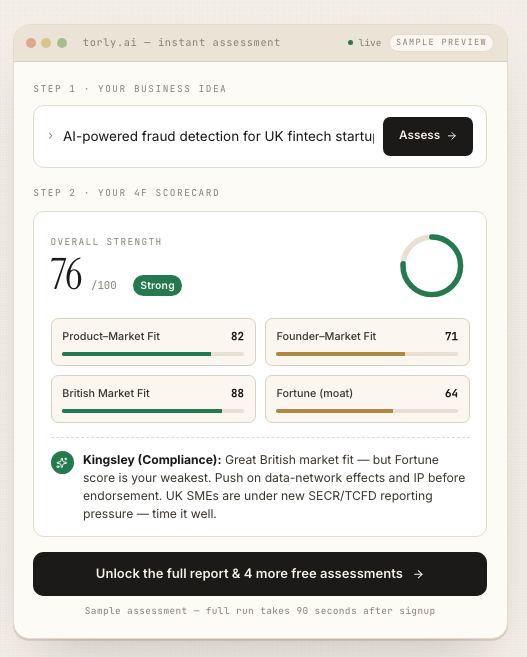
When payment networks give autonomous code the ability to initiate real-world financial settlements, traditional merchant systems must evolve. But here is the catch: innovation moves at lightspeed, while immigration policy moves at bureaucratic pace. When an applicant explains an autonomous agent payment protocol to an endorsing body assessor, the assessor looks for governance, fraud liability, anti-money laundering controls, and realistic customer acquisition models. If you want to articulate this complex business model without drowning in legal and technical debt, you need to Build your Business Plan NOW using dedicated tools that translate autonomous code into structured commercial strategy.
Deconstructing the UK Innovator Founder Visa Criteria for AI Startups
Securing an endorsement for the UK Innovator Founder Visa requires meeting three statutory benchmarks. Miss one, and your endorsement application will be refused:
1. Innovation
You cannot simply launch another online payment gateway. You must prove that your venture brings something genuinely original to the UK market. In the context of agentic commerce, innovation means solving complex challenges such as autonomous spend limits, agent identity governance, or machine-to-merchant payment rails that do not exist domestically.
2. Viability
Your venture cannot remain an academic research experiment. You need realistic cash flow forecasts, operational budgets, and evidence that you have the skills, capital, and technical architecture to make it run. Endorsing bodies examine your operational margins, customer acquisition costs, and compliance provisions (such as UK GDPR and FCA registrations).
3. Scalability
The Home Office expects job creation and international expansion. A solo developer running a script on a server will not suffice. You must show a clear roadmap for hiring high-value UK talent, expanding into European markets, and creating scalable revenue pipelines.
To satisfy these strict pillars, you must ensure your underlying data is bulletproof. The TorlyAI BP Builder APP helps tech founders align their technical documentation with these statutory criteria, ensuring no critical compliance gap gets overlooked.
Common Pitfalls: Why 90% of Fintech Founder Plans Get Rejected
Every year, thousands of brilliant software engineers and startup founders apply for UK endorsement, only to face swift rejections. The reasons rarely stem from weak technology; they stem from poor communication and strategic misalignment.
The most frequent mistakes include:
* Over-indexing on code architecture while ignoring the operational business model.
* Neglecting UK regulatory obligations, such as Financial Conduct Authority (FCA) oversight for autonomous financial instruments.
* Pitching unrealistic financial projections without explaining user acquisition costs or cohort retention.
* Failing to demonstrate why the UK is the natural base for the company, as opposed to Silicon Valley or Singapore.
* Submitting generic, templated business proposals that do not address the unique priorities of approved endorsing bodies.
Immigration rules evolve constantly. Trying to craft a compliant proposal using outdated guides or basic word processors is a recipe for delay. By leveraging AI Driven Visa Intelligence, you evaluate your venture against real-time endorsement expectations, identifying weaknesses in your pitch long before an assessor flags them.
The Three Pillars of Intelligent Visa Readiness
Navigating the endorsement landscape requires systematic validation. Rather than guessing whether your agentic startup measures up, smart teams break the process down into three analytical dimensions:

1. Business Idea Qualification
Before drafting hundreds of pages, your core premise must undergo rigorous scrutiny. Does the autonomous payment engine satisfy the Home Office’s strict definition of novelty? Is it merely an API wrapper around an established processor, or does it deliver a genuine technological leap? Specialist assessment models stress-test your value proposition against existing market competitors.
2. Applicant Background Assessment
An endorsement is awarded to the founder, not just the code. Endorsing bodies evaluate your technical background, leadership history, and proven capability to scale a company. Assessing your founder profile helps highlight leadership credentials, prior exits, open-source contributions, and research publications that establish your founder suitability.
3. Gap Identification and Strategic Roadmap
Once your strengths and weaknesses are mapped, you need an actionable strategy to address every shortfall. This includes refining your go-to-market plan, structuring your advisory board, detailing your UK hiring trajectory, and strengthening your balance sheet. With the right platform, you can Build your Business Plan NOW with concrete milestones that satisfy both technical partners and immigration assessors.
Step-by-Step: From Agentic Code to Endorsement Ready Plan
Transforming an autonomous commerce concept into an approved endorsement pack involves a disciplined sequence:
- Define the Machine Economy Problem: Explain why existing fiat systems fail autonomous software agents. Highlight systemic issues like manual card authorisations, lack of agent identity, and latency.
- Detail the Proprietary Solution: Clearly outline your governance guardrails, spending limits, cryptographic verification layers, and payment network integration.
- Establish Market Sizing: Calculate your Total Addressable Market (TAM), Serviceable Available Market (SAM), and Serviceable Obtainable Market (SOM) across both UK and European fintech corridors.
- Build the Financial Model: Provide sensible 3-year cash flow forecasts, break-even analyses, and scenario plans that factor in realistic hiring and operating overheads.
- Generate Compliant Documentation: Structure your proposal to reflect the exact evaluation templates used by authorised endorsing bodies.
By using the TorlyAI BP Builder APP, founders can move through these stages systematically, reducing document preparation time from several months to just a few days.
Preparing Your Venture for the Future of UK Innovation
The UK fintech ecosystem stands at a historic crossroads. As machine-to-machine transactions, decentralised rails, and autonomous software agents converge, the founders who establish their businesses today will define the next generation of global commerce. Endorsing bodies recognise this reality, but they need to see serious, well-structured, compliant applications from entrepreneurs who understand both the technology and the commercial fundamentals.
Do not allow bureaucratic uncertainty or weak documentation to derail your UK launch. Harnessing sophisticated evaluation systems transforms the endorsement journey from an opaque hurdle into a structured, predictable roadmap. By combining deep fintech innovation with modern AI Driven Visa Intelligence, you can substantiate your commercial vision, satisfy endorsing body standards, and establish your agentic enterprise in the heart of the UK’s thriving tech sector.