Business and Financial Planning Methodologies · October 14, 2026
AI-Powered UK Innovator Visa Application Assistant: Cash Flow Modelling and Financial Scenario Planning
Build bulletproof multi-scenario financial forecasts and protect your cash runway with the AI-Powered UK Innovator Visa Application Assistant modeling tool.
Why Most Innovator Founder Financial Forecasts Fail at Endorsement
Here is an uncomfortable fact for early-stage entrepreneurs: cash issues cause roughly 40% of startup failures, and endorsing bodies know it. When assessing an endorsement application for the UK Innovator Founder Visa, assessing panels do not just look at how clever your software is or whether your product sounds exciting. They scrutinise your cash runway, your burn rate, and your assumptions about the future. If your financial tables assume steady, uninterrupted revenue growth from month two without any safety buffer, your credibility evaporates immediately. Demonstrating structured Innovator Founder Scenario Planning inside your documentation is the single most effective way to prove your venture is viable, scalable, and resilient against real-world shocks.
Predicting the financial future of a completely new business model in a foreign market feels daunting. You are trying to forecast product development cycles, local hiring costs, UK tax liabilities, and customer acquisition benchmarks before you have even landed at Heathrow. Fortunately, modern reasoning models make this process straightforward. By combining real-time market data with automated stress tests, you can show assessors that your business will survive delayed pilot programmes, slow-paying enterprise clients, or regulatory hurdles. This guide breaks down the core mechanics of runway protection, scenario modelling, and how to use advanced tools to build financial projections that meet strict Home Office standards.
The Endorsement Reality: Viability and Scalability Under Scrutiny
Securing an endorsement letter requires meeting three core criteria set by the Home Office: innovation, viability, and scalability. Most founders spend 90% of their energy proving innovation. They draft long product descriptions, file patents, and detail technical architectures.
Yet, endorsement rejections frequently cite viability.
What does viability mean to an endorsing body? It means you have genuine commercial traction potential and enough capital to survive until cash flow positive. Scalability means your operation can grow rapidly across regional or international markets without operational costs matching your revenue trajectory one-to-one.
Your numbers must reflect these two principles directly:
- Viability metrics: Cash break-even points, monthly burn rate, working capital buffers, and realistic UK salary structures.
- Scalability metrics: Gross margin expansion, declining customer acquisition costs (CAC) over time, and software or production leverage.
If your financial plan shows zero marketing spend but forecasts £2 million in Year 2 ARR, assessing officers will reject it. If you do not account for VAT cycles, National Insurance contributions, or delayed enterprise payment terms, your cash runway will look fictitious. You can simplify this complex baseline setup when you Build your Business Plan NOW using intelligent planning templates configured for endorsing body criteria.
Cash Runway and Burn Rate: Calculating Survival, Not Fantasy
Cash runway is the exact amount of time your business can operate before it runs out of cash in the bank. Net burn rate is the net loss of cash your company records each month.
Many early-stage founders mix up gross burn with net burn. Gross burn is total operating expenditure per month (salaries, office space, cloud hosting, legal retainers). Net burn is gross burn minus monthly revenues. In the first year of an innovative startup, your net burn is usually identical to your gross burn because revenues take time to build.
Consider this standard UK scenario:
You hold £60,000 in personal investment funds or initial share capital. Your monthly operating costs sit at £5,000. On paper, you have 12 months of runway.
Now introduce commercial reality:
- Companies House filing fees, legal setup, and banking setup eat £2,500 upfront.
- A required proof of concept (PoC) takes 4 months longer than planned, delaying customer sign-ups.
- Your enterprise clients operate on 60-day invoice settlement terms.
Suddenly, that 12-month runway shrinks to 6 months before your first invoice is even paid. If your endorsement application does not explicitly document how your startup survives these timeline variations, assessors will question your commercial management capability.
The Three Core Scenarios Every Founder Must Model
Endorsing bodies want to know that you are not banking on pure luck. To prove this, your business plan must contain three distinct operational models.
1. The Base Case (The Realistic Target)
This is your realistic projection. It assumes standard product release milestones, average customer conversion rates based on competitor research, and moderate hiring schedules. It reflects steady, achievable progress where your marketing campaigns produce industry-standard metrics.
2. The Downside Case (The Stress Test)
What happens if customer acquisition costs spike by 40%? What happens if your main development milestone is delayed by a quarter? The downside scenario proves that your business does not collapse the moment something goes wrong. It details specific cost-cutting levers, such as pausing secondary recruitment, renegotiating cloud infrastructure commitments, or pivoting to higher-margin consulting revenue to preserve core development cash.
3. The Scaled Upside Case (The Hypergrowth Model)
If your enterprise pilots convert twice as fast as expected, do you run out of working capital trying to service them? Rapid expansion carries its own cash traps. You might need to hire five support engineers before enterprise licence payments arrive. The upside model shows that you can manage working capital requirements without sudden, emergency equity dilution.
Building all three versions manually in complex spreadsheets often leads to broken cross-sheet links and calculation discrepancies. Using a dedicated AI-Powered UK Innovator Visa Application Assistant guarantees that your underlying assumptions update synchronously across all three cases, preventing embarrassing errors during your interview.
Key UK Financial Realities to Include in Your Projections
International entrepreneurs often import financial assumptions from their home markets that do not fit the British regulatory or operational environment. Here are the specific financial line items endorsing bodies look for:
- Employer National Insurance (NI) Contributions: You cannot simply budget gross salaries. As an employer, you must pay secondary Class 1 National Insurance contributions on earnings above the secondary threshold.
- Workplace Pension auto-enrolment: Qualifying UK staff must be enrolled into a workplace pension scheme, with mandatory minimum employer contributions.
- Corporation Tax: The main rate of UK Corporation Tax sits at 25% for taxable profits over £250,000, with a small profits rate of 19% for profits under £50,000, and marginal relief between the two. Your net profit after tax must reflect this accurately.
- VAT Cash Flow Timing: Standard UK VAT is 20%. Depending on whether you use quarterly standard accounting or cash accounting schemes, timing differences between invoicing customers and remitting VAT to HMRC can dramatically impact month-end bank balances.
- Research and Development (R&D) Tax Relief: If you plan to claim R&D relief, avoid listing the cash credit in month one. Claims are settled retrospectively after financial year-end reviews, meaning you cannot rely on R&D tax refunds for early operational runway.
Addressing these specific costs shows the endorsement committee that you understand how business operations actually run within the United Kingdom.
How AI Speeds Up Financial Modelling and Validation
Traditional visa consultancy services charge thousands of pounds to prepare financial models, often taking weeks to deliver static spreadsheets that cannot easily adapt when your pricing strategy shifts.
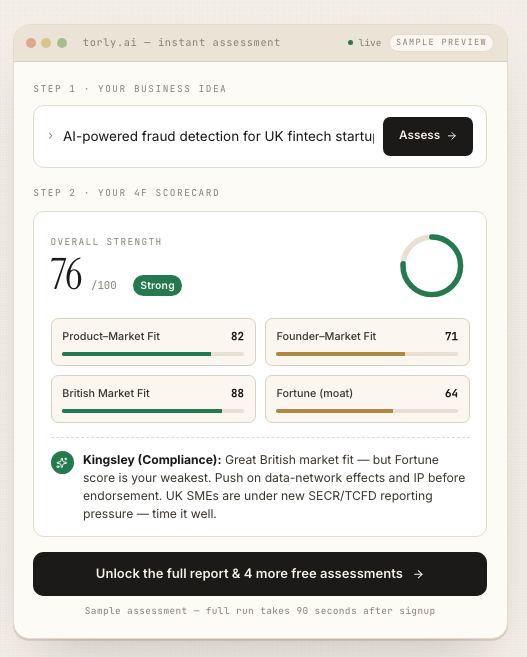
Torly.ai approaches this problem differently. As an advanced evaluation platform designed specifically for the Innovator Founder route, it uses next-generation reasoning agents to test your business idea, profile suitability, and cash projections against actual endorsement trends.
Instead of guessing what an endorsing body wants to see, you can utilise TorlyAI BP Builder APP to produce continuous, synchronized financial projections that mirror your operational narrative perfectly. The system uses specialised reasoning agents to evaluate your business across three critical layers:
- Idea Qualification: Assesses whether your product, pricing, and gross margins fit the official definition of an innovative, scalable venture.
- Founder Suitability: Checks if your professional background justifies your commercial growth targets.
- Gap Analysis: Identifies risks in your cash runway, highlight unrealistic conversion numbers, and provides specific recommendations to adjust your working capital model before submission.
By simulating how different market scenarios affect your cash flow, you eliminate guesswork and build a submission that stands up to detailed technical cross-examination.
Step-by-Step: Constructing Your Dynamic Financial Plan
To create an endorsement-ready cash flow forecast, follow this operational sequence:
Step 1: Establish Your Core Fixed and Variable Overheads
Separate costs into essential survival expenditures and expansion-driven investments. Fixed costs include your basic company registrations, essential software licences, insurance, and minimal founder living expenses. Variable costs include ad spend, contractor fees, cloud compute resources, and event marketing.
Step 2: Build a Bottom-Up Revenue Architecture
Do not write: “We will capture 1% of the UK software market.” That is a top-down assumption that endorsement officers reject on sight.
Instead, build from the bottom up:
* How many targeted outbound emails will you send per week?
* What is your expected reply and meeting rate (e.g., 2-3%)?
* How many discovery calls lead to a paid pilot (e.g., 10%)?
* What is the average contract value (ACV) of that pilot?
* How long is the enterprise sales cycle (e.g., 90 to 180 days)?
Multiplying these steps together produces a defensible, bottom-up revenue projection.
Step 3: Integrate Realistic Scenario Triggers
Decide in advance what decisions you will make when key performance indicators deviate from the base plan. If revenue at Month 6 is below 70% of target, define the exact mitigation step in your documentation. For instance: “Founder salary drops to statutory minimum, discretionary marketing shifts entirely to organic partnership channels, and product release 2.0 moves back by 60 days.”
Assessing bodies respect this level of operational discipline. It proves you understand how to manage risk under commercial pressure.
Protecting Your Runway: Equity, Dilution, and Alternative Capital
Founders often assume that the only way to fund an Innovator Founder venture is through rapid venture capital rounds. While early institutional investment is a strong signal, relying on hypothetical future equity rounds to balance your cash flow forecast is dangerous.
Endorsing bodies want to see that your business can function even if a venture capital round takes nine months to close. You must demonstrate how you balance equity dilution with sustainable commercial income:
- Founder Share Capital: Clearly verify the source of your initial investment funds in line with Home Office anti-money laundering regulations.
- Grant Funding: The UK has rich non-dilutive grant options (such as Innovate UK Smart Grants). If you include grants in your cash flow model, treat them as upside bonuses rather than guaranteed operational cash.
- Customer-Funded Development: Where possible, design pilot programmes where enterprise clients cover initial implementation costs. This proves market demand while extending your runway organically.
By showing multiple pathways to sustain working capital, your cash flow forecast moves from a hopeful presentation into an actionable corporate plan.
Conclusion: Take Command of Your Financial Readiness
An endorsement-ready financial model is far more than a compliance document for the UK Home Office. It is your strategic operating blueprint. By taking control of your burn rate, understanding local UK tax mechanisms, and running rigorous multi-case scenario analyses, you protect both your visa eligibility and the long-term future of your enterprise.
You do not need an expensive investment banking team to prepare institutional-grade financial forecasts. With specialized tools designed to map out dynamic business models, you can test every assumption, eliminate viability risks, and walk into your endorsement review with complete confidence.
Take the uncertainty out of your numbers today and AI-Powered UK Innovator Visa Application Assistant your pathway to endorsement-ready financial compliance.