AI Governance and Compliance · September 23, 2026
AI-Powered UK Innovator Visa Application Assistant: Navigating Bank of England AI Standards for Visa Endorsement
Discover how AI-Powered UK Innovator Visa Application Assistant analyses Bank of England AI governance frameworks to ensure your FinTech business plan meets strict endorsing body standards.
Why FinTech Founders Are Getting Rejected (And How to Fix It)
Landing a UK Innovator Founder Visa has never felt more challenging. If you are pitching a financial technology startup, the bar is ridiculously high. Endorsing bodies are no longer impressed by generic buzzwords or surface-level machine learning wrappers. They want to see real innovation, solid commercial viability, and ruthless regulatory compliance. When your FinTech plan mentions automated lending, algorithmic trading, or fraud detection, endorsing bodies check whether your technology aligns with institutional realities. Specifically, they look at the governance benchmarks shaped by the Bank of England and the Prudential Regulation Authority.
Building a pitch that satisfies both immigration criteria and strict central bank standards feels like walking a tightrope. This is where an intelligent platform changes the game. By testing your proposal against actual Home Office metrics and regulatory standards through an AI-Powered UK Innovator Visa Application Assistant, you can pinpoint systemic gaps long before an endorsing body sees your file. You do not just need a business plan; you need a model that proves your algorithmic governance, operational resilience, and compliance are completely airtight.
The Reality of Bank of England AI Frameworks in 2026
Let us be honest for a second: the Bank of England does not regulate your visa directly. The Home Office and legacy endorsing bodies handle that. But endorsing bodies do not operate in a vacuum. When assessing whether a business is viable and scalable, they measure your operations against modern UK financial standards.
Recent supervisory frameworks from the Bank of England and the Financial Conduct Authority (FCA) outline clear boundaries for using artificial intelligence in financial services:
- Model explainability and auditability: Black-box algorithms making credit, investment, or underwriting decisions are dead on arrival. You must demonstrate how your model reaches its conclusions.
- Data integrity and non-bias: The Bank places massive emphasis on data hygiene. Algorithms trained on skewed, unvetted datasets face immediate operational shutdown.
- Third-party risk management: Under Supervisory Statement SS 2/21, relying on external cloud providers or foundation model APIs requires documented fallback mechanisms.
- Agentic AI governance: If your FinTech uses autonomous agents that interact with markets or handle user funds, you need human-in-the-loop safeguards to prevent unexpected feedback loops.
If your pitch merely promises “disruptive automated underwriting” without showing how it respects these supervisory guidelines, an assessor will flag your project as high risk. You will fail the viability test instantly.
The Endorsing Body Dilemma: Innovation vs Compliance
Securing an endorsement requires satisfying three statutory criteria: Innovation, Viability, and Scalability.
Here lies the paradox for FinTech entrepreneurs. To prove innovation, you want to pitch cutting-edge, autonomous systems. You want to highlight deep reinforcement learning or autonomous agentic workflows. But to prove viability, you must show absolute stability, risk control, and legal compliance.
Push too hard on novel experimentation, and your viability score collapses under regulatory risk. Play it too safe with standard spreadsheets, and your innovation score flatlines.
To bridge this gap, founders are stepping away from static consultant templates. Instead, you can Build your Business Plan NOW using intelligent systems that balance high-level technical innovation against the exact compliance checks endorsing bodies demand.
Where Traditional Visa Consultants Drop the Ball
Most standard immigration consultants do a decent job checking whether your passport scans are legible or whether your bank statements cover maintenance funds. But ask a generalist visa solicitor how a multi-agent financial model complies with the Bank of England’s operational resilience rules, and you will get blank stares.
Traditional consultancy falls short in three distinct areas:
- Technical ignorance: General consultants do not understand how transformer models, vector databases, or decentralized ledgers work. They cannot help you defend your core intellectual property during an endorsement interview.
- Slow iterations: The market shifts quickly. If an endorsing body updates its focus toward third-party model risk, a human consultant might take weeks to rewrite your commercial narrative.
- No predictive scoring: You hand over thousands of pounds without knowing your mathematical probability of success. It is entirely subjective.
Founder readiness requires a technical, data-driven assessment. Evaluating your operational background against historic application data using a dedicated UK Innovator Success Predictor provides actionable clarity. It takes the guesswork out of the equation.
Breaking Down the Core Requirements: Innovation, Viability, Scalability
Let us look closely at how the Bank of England’s supervisory philosophy directly mirrors the Home Office criteria.
1. Innovation: True Differentiation
Your product cannot simply be an off-the-shelf chatbot hooked up to an existing banking API. The Bank of England is actively studying how foundation models and generative AI affect market stability. Endorsing bodies look for genuine intellectual property.
- What custom logic or proprietary weights have you developed?
- Why can an established high-street bank not simply build this next week?
- How does your system solve an authentic market friction in the UK economy?
2. Viability: Financial and Operational Resilience
Viability is where most AI startups stumble. The Bank of England’s Financial Stability in Focus reports continuously warn against correlated model failures and opaque automated decisions.
Your business plan must explain how your startup manages model drift, data poisoning, and cloud downtime. If you cannot outline your testing, validation, and disaster recovery processes, an endorsing body will determine your business cannot survive in the real UK market.
3. Scalability: Employment and Market Growth
Scalability requires showing planned growth within the UK domestic market alongside international expansion. The Home Office wants to see skilled job creation. For FinTech companies, that means hiring local machine learning engineers, compliance officers, and risk specialists. You must clearly tie your revenue projections to direct job creation over years one, two, and three.
To assemble documentation that weaves these three threads into a coherent application, you can use the TorlyAI BP Builder APP to ensure every chapter mirrors regulatory expectations.

How Torly.ai Analyses Your Endorsement Readiness
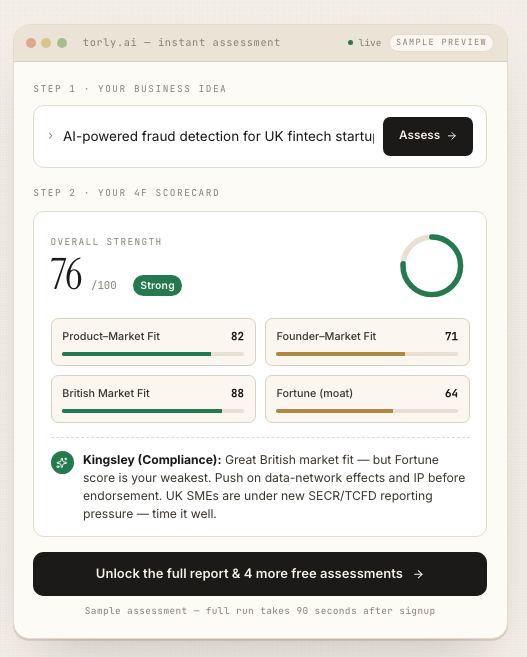
Torly.ai was built specifically to resolve the disconnect between raw entrepreneurial ideas and rigid UK visa rules. Rather than offering basic proofreading, the platform acts as an automated readiness analyst.
The engine works across three distinct stages:
- Business Idea Qualification: It stress tests your proposed venture against active Home Office rules and historical endorsing body decisions. If your AI platform touches sensitive consumer credit data without adequate governance structures, the system flags the issue instantly.
- Applicant Background Assessment: It analyses your professional experience, technical credentials, and entrepreneurial track record to see if you meet the profile expected for a lead tech founder.
- Gap Identification and Action Roadmap: It does not simply tell you what is wrong. It generates concrete steps to shore up your technology stack, clarify your revenue model, and fortify your operational resilience narrative.
By simulating the scrutiny of an endorsing body panel, founders gain a multi-layered evaluation long before submittal.
Essential Steps to Prepare Your FinTech Application
If you are developing a technical proposal right now, follow these steps to keep your plan aligned with modern governance expectations:
- Clarify human oversight: Explicitly document where human decision-makers override automated algorithms. Show who holds regulatory accountability.
- Detail your data pipeline: Detail your data sources, preprocessing steps, and bias-testing routines. Show respect for UK GDPR and financial industry security standards.
- Map third-party dependencies: Document the backup plans you have in place if a critical cloud provider or foundation API suffers an outage.
- Structure realistic financials: Avoid wild hockey-stick projections that lack customer acquisition logic. Keep operational costs, developer salaries, and compliance overheads realistic for the UK market.
Taking the time to refine these details sets serious founders apart from superficial pitches. You can jumpstart this process and Download BP Build Desktop APP to structure your narrative through specialised workflows.
The Future of UK FinTech and Autonomous Systems
The UK remains one of the world’s premier destinations for technological and financial innovation. Initiatives like the Bank of England’s Digital Securities Sandbox and its ongoing explorations into distributed ledgers prove that regulators welcome progress. They simply want that progress managed responsibly.
For immigrant founders, the message is plain: build ambitiously, but govern strictly. When you show endorsing bodies that your AI startup understands both high-velocity product execution and conservative systemic risk management, you turn a risky visa application into an undeniable endorsement candidate.
Before submitting your file to an endorsing panel, test your metrics, refine your technical documentation, and ensure you are completely ready with the Torly.ai Visa Readiness Platform.