Banking Data Platforms · October 6, 2026
AI-Powered UK Innovator Visa Application Assistant: Open Banking Innovation Roadmap for Founder Endorsement
See how AI-Powered UK Innovator Visa Application Assistant guides open finance innovators in proving regulatory compliance and robust British market fit to endorsing bodies.
Navigating the Shift: Open Finance and Your Founder Journey
Securing an endorsement for the UK Innovator Founder Visa has never been about ticking boxes. It is about proving that your enterprise brings genuine innovation, market viability, and scalable potential to the British economy. With the Competition and Markets Authority (CMA) confirming the full completion of the original Open Banking roadmap, the bar has shifted dramatically. Building basic API connections is no longer enough to impress an endorsing body. Today, founders must show deep regulatory alignment, smart consumer data utility, and an airtight commercial strategy. Navigating this transition requires strategic clarity, which is why founders rely on the AI-Powered UK Innovator Visa Application Assistant to craft a compliant UK Innovator Roadmap that meets modern Home Office benchmarks.
This milestone signals the move from mandatory compliance by the CMA9 banks to a wide-open landscape of open finance and variable recurring payments (VRP). If you are building a fintech, banking data platform, or software product in this space, endorsing bodies want to see how your venture leverages enriched data safely. You need to prove customer traction, financial viability, and strict adherence to Financial Conduct Authority (FCA) expectations. Piecing together these technical and regulatory puzzles takes precision, but leveraging an automated readiness assessment ensures you do not leave your founder endorsement to chance.
What the Completion of the CMA Open Banking Roadmap Actually Means
For years, UK open banking was stuck in infrastructure mode. Regulators forced the largest nine retail banks to open up their customer data through secure APIs. That phase is finished. The foundational plumbing is installed, tested, and active across millions of consumer and business accounts.
Now, the market has pivoted toward open finance. The regulatory steering wheel is moving from the initial implementation entity to permanent oversight under the Smart Data council, the FCA, and the Payment Systems Regulator (PSR).
What does this mean for international founders?
- Core API aggregation is commoditised: Simply fetching bank statements via an API is no longer considered novel or innovative by endorsing bodies.
- Value-added data processing is king: The real opportunity lies in categorisation, predictive credit intelligence, automated cash-flow forecasting, and automated accounting workflows.
- Advanced payment rails are expanding: Non-sweeping variable recurring payments (VRP) are replacing direct debits and card-on-file transactions.
- Regulatory compliance has tightened: Endorsing bodies expect your business plan to articulate how you handle data protection, consumer duty rules, and technical risk.
To stand out, your application must explain how your platform solves real market friction. If you are preparing your technical narrative and market analysis, you can Build your Business Plan NOW to ensure every regulatory nuance aligns with endorsing body priorities.
The Endorsement Dilemma: Innovation, Viability, and Scalability
Endorsing bodies in the UK evaluate your venture against three strict criteria: innovation, viability, and scalability. Many fintech founders stumble because they treat these criteria like academic essays rather than commercial proofs.
Innovation
Innovation does not mean inventing a whole new mathematical algorithm. It means offering a genuine market disruption or a distinct competitive advantage within the UK. In the context of open banking, this means using enriched financial data to solve structural issues, such as reducing lending fraud for underserved SMEs or automating niche B2B reconciliations.
Viability
Can you actually build and sell this? Endorsing bodies scrutinise your operational runway, your technical milestones, and your regulatory awareness. If you claim you will launch an FCA-regulated payment service without capital or a clear compliance partner, assessors will mark your application down instantly.
Scalability
Does the business have high-growth potential? You must prove job creation potential, national market reach, and clear international expansion plans. A regional consulting shop will not pass; a scalable software platform leveraging automated data pipelines will.
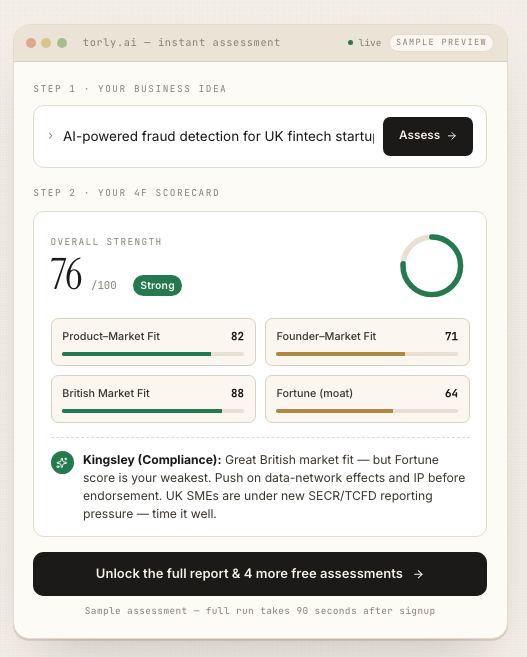
Reviewing these criteria manually takes months of trial, error, and expensive legal consultations. That is why an intelligent evaluation engine like Torly.ai acts as an automated readiness analyst. It reviews your venture profile across all three dimensions, spotting critical weaknesses before you present your case to an external assessor.
Bridging the Gap with Multi-Agent AI Architecture
Drafting a complete visa application pack involves deep technical architecture, granular financial projections, competitor matrices, and immigration-compliant narratives. Doing this alone often leads to disjointed documentation where the financial model contradicts the product roadmap.
Specialised artificial intelligence changes this dynamic. Rather than using generic prompts, a dedicated multi-agent system divides the workload into distinct functional domains. One agent audits the technical feasibility of your software architecture, while another cross-examines your market sizing against current UK industry reports.
If you want a seamless route from early concept to an investment-ready document bundle, you can test the TorlyAI BP Builder APP to coordinate complex application components in one unified workspace.
By running continuous validation checks, AI systems compare your proposal against recent endorsing body decisions. They flag vague market definitions, unrealistic revenue timelines, or missing compliance protocols. This eliminates blind spots and provides you with dynamic scoring based on current immigration standards.
Step-by-Step UK Innovator Roadmap for Fintech and Data Founders
Building an endorsement-ready venture while preparing to relocate to the UK requires a clear, linear plan. Here is the operational framework you should follow:
Phase 1: Problem Validation and Architecture Design
Map your data flow clearly. If your application relies on European or British open banking APIs, explain whether you operate as an Account Information Services Provider (AISP), a Payment Initiation Services Provider (PISP), or an agent under an existing authorised umbrella. Document your data categorisation pipelines and security measures thoroughly.
Phase 2: Regulatory Stress Testing
Ensure your plan complies with UK General Data Protection Regulation (UK GDPR) and upcoming Smart Data initiatives. Assessors will look for clear explanations of customer consent management, cryptographic safeguards, and tokenisation flows.
To make sure your operational roadmap hits every mark expected by assessors, align your business milestones with the official UK Innovator Roadmap guidance early in the development cycle.
Phase 3: Comprehensive Documentation Compilation
Your submission package must contain a coherent business plan, cash flow projections, sensitivity tables, founder CVs, and technical whitepapers. The figures must match across every document. If your marketing plan projects 10,000 active users by month six, your cloud infrastructure costs and customer acquisition budgets must reflect that reality.
Phase 4: Pitch Preparation and Endorsement Submission
Once your portfolio passes readiness checks, submit your application to the designated endorsing body. Be prepared for rigorous interviews where panel members probe technical risk, team defensibility, and cash burn rate.
Common Pitfalls Open Finance Applicants Must Avoid
Even seasoned founders make avoidable mistakes when pitching open banking solutions to UK endorsing bodies:
- Over-relying on basic data access: Simply presenting an account aggregation dashboard does not meet the innovation standard. Focus on what happens after the data is pulled.
- Ignoring the regulatory perimeter: Claiming you do not need FCA authorisation when handling client funds or initiating automated payments will cause immediate rejection.
- Overly optimistic traction metrics: Showing hockey-stick user growth without detailing customer acquisition channels, cost per install (CAC), or distribution partnerships damages your credibility.
- Generic competitor evaluations: Dismissing established legacy players or established aggregators as irrelevant shows poor market awareness. Highlight your technical wedge instead.
Using automated assessment tools lets you detect these logic gaps within minutes rather than discovering them through a formal visa rejection letter.
Accelerate Your Path to UK Endorsement
The UK remains one of the world’s most dynamic environments for fintech and data-driven businesses. The completion of the CMA Open Banking roadmap opens up massive commercial avenues for smart data platforms, predictive intelligence engines, and automated business workflows.
However, navigating the endorsement criteria requires serious preparation, objective feedback, and flawless documentation. Do not let minor oversights or regulatory omissions derail your expansion plans. Use a dedicated intelligence platform to evaluate your market fit, refine your technical documentation, and build a bulletproof application that stands up to professional scrutiny.
Take the first step toward launching your UK enterprise today by securing your UK Innovator Roadmap assessment and presenting your business vision with absolute confidence.