AI Finance Assistants · October 3, 2026
Building a FinTech Venture in the UK: Accelerate Endorsement with Torly.ai
Explore how Torly.ai equips AI personal finance innovators with robust business planning and endorsing body compliance to obtain the UK Innovator Founder Visa.
The FinTech Dream: Why Your AI Personal Finance Pitch Needs More Than Great Vibes
Let us be completely honest for a moment. Creating a consumer-facing financial app sounds incredible on paper. You look at consumer darlings like Cleo, with their witty conversational budgeting, automatic spending trackers, and viral “Roast Mode” that shames people for buying iced lattes, and you think: I can build an AI personal finance tool that does that, but smarter. Cleo proved that young spenders hate traditional high-street banks and prefer chatting with a witty bot. But if you want to set up shop in London or Edinburgh as a foreign founder, having a cute bot concept is not enough. You need an ironclad AI finance business plan that convinces official British assessing bodies you are launching a genuine powerhouse, not just a flashy wrapper on top of an existing LLM.
Moving from a prototype to a legally backed UK business means surviving the dreaded Innovator Founder Visa process. The Home Office does not care if your bot can make Gen Z laugh on TikTok; their endorsing bodies demand ruthless proof of innovation, viability, and scalability. To bridge this massive gap between a clever consumer app idea and regulatory approval, smart entrepreneurs run their concepts through an AI Visa Desktop App to pressure-test their viability before submitting a single form. Navigating this ecosystem requires clear thinking, genuine market differentiation, and an understanding of what endorsing bodies actually look for.
The Cleo Playbook vs Endorsement Reality
Cleo nailed user engagement. By combining gamified saving, credit-building tools, paycheck advances, and snappy dialogue, they turned boring personal budgeting into a habit. If you are developing an AI finance assistant, studying their playbook makes absolute sense. Users want frictionless banking integrations, plain-English advice, and predictive spending alerts that stop them from blowing their rent money.
Here is the catch: what flies on the App Store will flatline in an endorsing body interview if that is all you bring.
When an endorsing body reviews an AI finance business plan, they evaluate your company across three strict UK Home Office criteria:
- Innovation: You cannot just reskin an existing open-source language model or plug into a standard Open Banking API. You need proprietary tech, custom agent workflows, or a unique approach to predictive financial modelling.
- Viability: Does your financial model reflect realistic customer acquisition costs (CAC) in the UK? How will you handle Open Banking data regulations under the Financial Conduct Authority (FCA)?
- Scalability: Can this venture create high-skilled UK jobs and expand internationally, or will it remain a one-person lifestyle venture?
Cleo spent years raising venture capital and perfecting their compliance architecture to make their casual persona work safely. If you try to replicate that manually in a Word document, you will spend months untangling regulatory knots. That is why so many technical founders choose to Build your Business Plan NOW using intelligent systems designed to map technical architecture directly to Home Office expectations.
Why Most AI FinTech Business Plans Get Rejected
Every year, hundreds of bright founders pitch brilliant financial apps and walk away empty-handed. The failure rarely stems from bad code. It almost always stems from a weak, non-compliant business pitch. Here are the regular pitfalls:
1. The “Thin Wrapper” Trap
If your core value proposition relies solely on sending user transaction data through a basic third-party API, endorsing bodies will spot it instantly. They want to know what your intellectual property actually is. Where is the proprietary scoring model? What bespoke algorithms are you deploying locally?
2. Ignoring UK Financial Compliance
You cannot pitch personal financial advice without addressing the regulatory sandbox. Will you operate as an Account Information Services Provider (AISP)? Are you partnering with an authorised umbrella firm? If your documentation skips over compliance, your application goes straight into the rejection pile.
3. Vague Scaling Metrics
“We will get 100,000 users via social media ads in Month 3.” No, you will not. Endorsing bodies see through inflated vanity metrics. They expect detailed cohort analyses, projected customer lifetime values, and sensible hiring timelines for domestic UK talent.
To avoid these traps, successful applicants do not rely on standard document templates. Instead, they lean on a dedicated AI-Powered UK Innovator Visa Application Assistant that actively hunts down logical gaps in their revenue models, market sizing, and compliance structures before human evaluators ever see them.
The Three Pillars: Structuring Your AI Finance Business Plan
To pass the bar, your documentation must treat product design and regulatory strategy as two halves of the same whole. Let us break down how you should structure your proposal to win over the strictest assessors.

1. Market Research and Problem Identification
Start with the systemic problem. For instance, young professionals in Britain are struggling with the cost-of-living crisis, complex student loans, and fragmented credit reporting systems.
Explain why existing budgeting tools fall short:
* Static charts fail to motivate behavioural change.
* Traditional bank apps hide fees and offer zero predictive forecasting.
* First-generation chatbots offer generic tips instead of hyper-personalised, data-driven interventions.
Show where your AI agent fits. Use concrete market data from the UK fintech sector, citing trends across Open Banking adoption, consumer credit movements, and digital banking shifts.
2. Technical Architecture & Proprietary Edge
Clearly describe your technology stack. Assessors want to see:
* How your platform ingests and encrypts Open Banking payloads.
* Your retrieval-augmented generation (RAG) pipelines or bespoke financial calculation engines.
* Data protection protocols that comply fully with the UK Data Protection Act and UK GDPR.
If you struggle to articulate how your technical architecture translates into visa-ready terminology, you can deploy the specialized TorlyAI BP Builder APP to draft comprehensive technical explanations tailored precisely to endorsement standards.
3. Financial Forecasts and Job Creation
Your financial forecast must be grounded in realism:
* Year 1: Prototype validation, regulatory registration, early beta testing with a small cohort, minimal revenue, founder investment.
* Year 2: Public launch, paid subscription tiers, introduction of premium credit-monitoring features, hiring your first two full-time UK developers.
* Year 3: Rapid scaling, potential international expansion, creating high-value jobs in engineering, operations, and compliance.
How Torly.ai Changes the Equation for Visa Applicants
Writing a document of this magnitude while simultaneously writing code, pitching angel syndicates, and managing life transitions is brutal. The market moves fast, and spending six months drafting a business plan by hand often means someone else launches your feature first.
This is precisely where Torly.ai enters the picture.
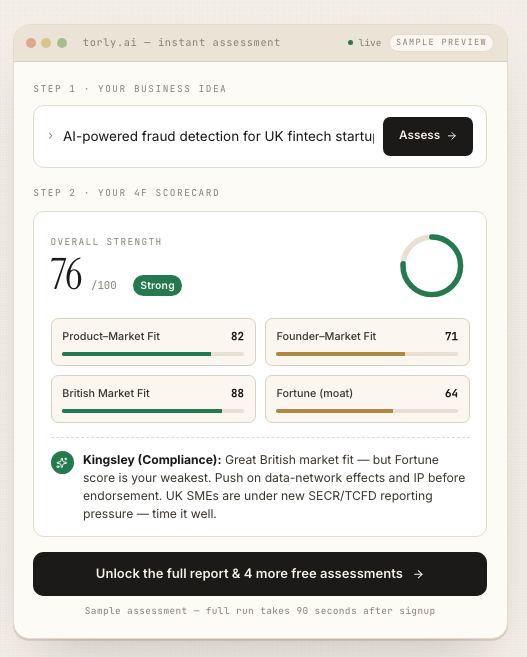
Torly.ai is not an ordinary text generator. It is an evaluation-driven platform built specifically around the UK Innovator Founder Visa framework. Powered by next-generation reasoning agents, it evaluates your credentials and your product concept just like an official endorsing body officer would.
The platform breaks down your evaluation into three distinct layers:
1. Business Idea Qualification: It runs your AI finance concept against real Home Office endorsement standards, checking for true innovation, defensible viability, and genuine scalability.
2. Founder Background Assessment: It reviews your technical background, commercial experience, and leadership track record to verify you fit the profile of a venture-backed founder.
3. Gap Identification & Roadmap: Instead of leaving you with vague advice, Torly.ai spots exact weaknesses in your customer acquisition funnel, unit economics, or compliance model, and gives you actionable steps to fix them.
Rather than guessing whether your plan meets official scrutiny, utilizing an innovative AI endorsement platform provides dynamic scoring based on historic data and current immigration policy shifts.
Beyond the Plan: Preparing for the Endorsement Panel
Writing your plan is only the first stage of the battle. Once your written application clears the initial desk review, you will face an endorsement interview. The assessing panel will interrogate every single metric you put down.
If your plan states your customer acquisition cost is £12, be prepared to defend it:
* What channels are you testing?
* What is your projected click-through rate?
* How does that compare to established personal finance apps?
If you mention automated credit recommendations, they will ask:
* How do you prevent algorithmic bias?
* What are your liabilities under consumer duty rules?
Because Torly.ai operates using multi-agent reasoning, it stress-tests your concept against these exact questions. It forces you to iron out weaknesses long before you sit in front of human assessors. If you want to streamline this preparation phase, you can Download BP Build Desktop APP to produce a robust, fully vetted document backed by structured agentic analysis.
Take the Fast Lane to Your UK Tech Venture
Building an AI personal finance assistant that rivals industry pioneers is an ambitious goal. The UK is one of the best places in the world to make it happen, boasting unmatched access to fintech capital, progressive regulatory sandboxes, and an eager consumer market.
Do not let administrative complexity, regulatory jargon, or visa hurdles kill your venture before it launches. Treat your immigration paperwork with the same engineering precision you bring to your product codebase.
Take the guesswork out of your journey today. Partner with an advanced AI Visa Desktop App to turn your innovative financial concept into a fully endorsed, market-ready UK business.