Startup Ecosystem Overviews · October 21, 2026
Building a Top UK Fintech Venture: AI-Powered UK Innovator Visa Application Assistant Insights
Benchmark your fintech venture against high-growth British startups and secure endorsing body backing with AI-Powered UK Innovator Visa Application Assistant.
Navigating UK Startup Visa Compliance for High-Growth Fintech
The UK remains one of the world’s most dynamic hubs for financial technology. From open banking infrastructure and digital payments to algorithmic wealth management, British seed-stage startups are securing substantial equity funding across London, Edinburgh, and Manchester. However, building an early-stage fintech company as an international founder requires clearing a formidable regulatory hurdle before taking in institutional capital: achieving absolute endorsement and immigration approval. Securing your founding pathway means meeting exact Home Office criteria, satisfying an authorised endorsing body, and establishing continuous UK Startup Visa Compliance from day one.
Many founders falsely assume that a slick pitch deck or a prototype app will guarantee endorsement. In reality, assessing bodies look past the hype to scrutinise your technology, genuine market differentiation, and commercial projections. To survive this vetting, modern entrepreneurs are turning to machine intelligence to pressure-test their documentation before human assessors ever lay eyes on it. Leveraging the AI-Powered UK Innovator Visa Application Assistant gives founders the predictive edge needed to align their ventures with official standards, ensuring your fintech enterprise stands alongside top-tier British companies while keeping every regulatory commitment watertight.
The Seed Fintech Landscape: What Makes British Ventures Stand Out?
The UK fintech ecosystem is famously competitive. Authorised data platforms tracking UK seed-stage companies reveal that the businesses raising the fastest rounds are not merely reskinned versions of existing consumer banking apps. Instead, the top performers focus heavily on resolving back-office friction, compliance bottlenecks, cross-border settlement speeds, and niche regulatory reporting.
When you examine the businesses that successfully scale, their value proposition usually rests on three foundational pillars:
- Deep Technological Defensibility: They possess proprietary algorithms, complex data pipelines, or automated compliance infrastructure rather than basic wrappers around public APIs.
- Clear Regulatory Awareness: They understand Financial Conduct Authority (FCA) parameters, data handling, and consumer duty regulations right out of the gate.
- Demonstrated Market Need: They solve pain points that traditional clearing banks and legacy software providers are simply too slow to tackle.
If you are developing a fintech venture, endorsing bodies will evaluate you against this exact standard. They want to see that your venture creates genuine economic benefit and skilled jobs within the domestic market.
The Innovator Founder Standard: Innovation, Viability, and Scalability
Endorsement is not a casual rubber stamp; it is a legal prerequisite governed by strict Immigration Rules. Endorsing bodies require you to demonstrate that your fintech concept satisfies three mandatory criteria:
1. Innovation
Your business cannot simply replicate an existing UK service. A white-label payments portal or a local remittance shop will not pass. Assessors look for proprietary tech, new operational models, or novel applications of machine learning that provide a clear competitive moat. Understanding competitor analysis that helps your case is critical here: you must articulate why incumbents cannot easily duplicate your offering.
2. Viability
Do you have the skills, background, and capital strategy to execute this plan? Assessors examine your unit economics, burn rate, and commercial milestones. Crucially, they verify whether you personally embody the capability to drive the enterprise forward. Establishing strong founder-market fit explained across your personal profile helps satisfy this viability pillar directly.
3. Scalability
A successful Innovator Founder enterprise must show significant growth potential. Endorsing bodies expect verifiable plans for national and international expansion, backed by structured hiring plans for settled UK workers. Your revenue forecasts must reflect realistic market dynamics rather than arbitrary hockey-stick curves.
To ensure your plan stands up to this level of scrutiny, you can explore the TorlyAI Desktop APP to draft, stress-test, and structure your submissions against formal requirements.
Avoiding Critical Compliance Pitfalls in Your Submission
Fintech business models carry higher regulatory scrutiny than simple software ventures. Endorsing bodies are acutely aware that financial platforms interact with sensitive personal data, anti-money laundering (AML) legislation, and payment rails.
A common pitfall among international entrepreneurs is submitting a business plan that fails to outline compliance milestones. If your application mentions processing payments, lending funds, or handling digital assets, assessors will expect a clear timeline for FCA permissions, such as payment institution authorisation or appointed representative status. Failing to account for these steps signals that the founder does not understand the British financial ecosystem.
Another frequent error is vague financial modelling. When presenting financial projections, remember that scenario planning beats a single forecast every time. You need base-case, best-case, and conservative models that account for development delays, regulatory filing periods, and customer acquisition costs.
Maintaining full regulatory alignment across all your initial paperwork is essential. Utilizing an AI-Powered UK Innovator Visa Application Assistant can highlight missing elements, calculate compliance risks, and identify weak spots in your operational framework well before you submit to an endorsing body.
Why Evaluating Your Readiness with AI Changes the Game
Preparing a compliant submission traditionally meant hiring expensive immigration solicitors and business advisors. While legal advice remains valuable, static consultancy often fails to capture the technical nuances of an AI or blockchain fintech product.
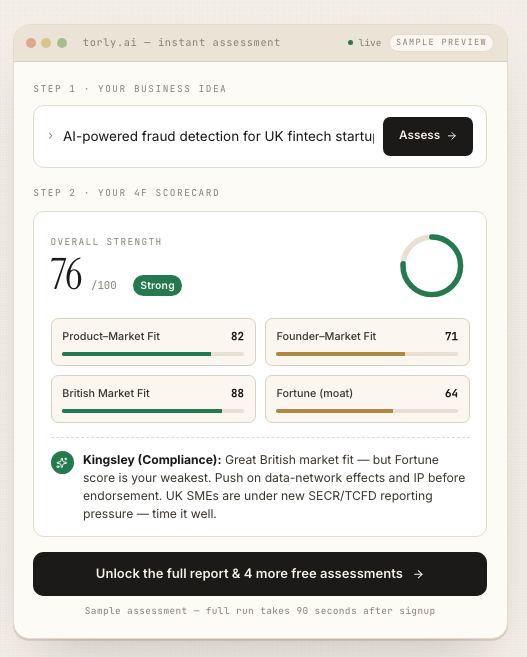
This is where specialised machine reasoning transforms the process. Advanced evaluation platforms assess your documents using the same criteria applied by real case officers.
Rather than guessing how an assessor might interpret your go-to-market strategy, evaluation platforms carry out instant multi-layered assessments:
- Business Qualification: Systematically scoring your fintech proposal against official Home Office guidelines for novelty and intellectual property protection.
- Applicant Background Check: Assessing your entrepreneurial track record and technical competencies to ensure your resume mirrors the requirements of your chosen vertical.
- Gap Identification: Pinpointing missing technical milestones, unrealistic financial assumptions, or regulatory voids, providing actionable fixes to rectify them.
You can streamline this entire drafting phase when you use the TorlyAI BP Builder APP, an agentic workspace that guides you systematically from conceptual notes to a fully reasoned, endorsement-ready asset.
Maintaining Active UK Startup Visa Compliance Post-Endorsement
Receiving your endorsement letter and obtaining your entry clearance stamp is only the beginning. The Innovator Founder route requires continuous engagement with your endorsing body. Unlike older visa streams, you cannot simply launch a lifestyle company and operate unchecked.
Endorsing bodies are legally required by the Home Office to monitor your progress through formal checkpoints, typically held at the 12-month and 24-month marks. During these reviews, you must prove that you are actively implementing your business plan.
To maintain ongoing UK Startup Visa Compliance, you must be prepared to demonstrate:
- Significant Milestones Achieved: Product releases, code deployments, merchant onboarding, or live beta tests.
- Job Creation and Spending: Proof of company expenditure, PAYE filings for UK employees, and appropriate corporate tax compliance.
- Founder Commitment: Evidence that you are acting as a day-to-day executive leader rather than a passive investor.
If your fintech business must pivot, as early-stage ventures often do, you must inform your endorsing body promptly. Unapproved deviations from your core business model can lead to endorsement withdrawal, curtailing your leave to remain in the country.
Scaling Your Venture into the British Market
Once compliance workflows are established, the UK provides exceptional opportunities for fintech founders. Between venture capital density, government-backed R&D tax incentives, and the global appeal of the City of London, high-growth ventures can build world-leading products from a British base.
Getting your foundation right protects your investment, your immigration status, and your company’s future. By taking a rigorous, technology-driven approach to your application and ongoing governance, you ensure that your business meets every regulatory test while scaling rapidly.
Ready to test your concept against official endorsing criteria? Validate your business model, benchmark your readiness, and master your UK Startup Visa Compliance with our complete suite of AI-driven tools designed to take you from initial idea to approved founder.