Fintech Platforms · October 1, 2026
Building Endorsement-Ready Financial Models: AI-Powered UK Innovator Visa Application Assistant Blueprint
Meet strict endorsing body financial criteria with AI-Powered UK Innovator Visa Application Assistant, delivering robust cash flow forecasts and viability models for fintech innovators.
Why Most Innovator Founder Visa Spreadsheets Fail at Endorsement
Securing endorsement for the UK Innovator Founder Visa rarely falls apart on raw passion; it crumbles inside a spreadsheet. Endorsing bodies assess hundreds of pitches from brilliant international founders who have fantastic product concepts, yet present completely unrealistic cash flow estimates, skewed unit economics, or vague overheads. If you are developing a fintech platform, payment rails product, or cross-border software tool, generic financial projections will kill your application immediately. You must demonstrate viable unit metrics, compliance reserves, and a cash runway that reflects real-world operational challenges.
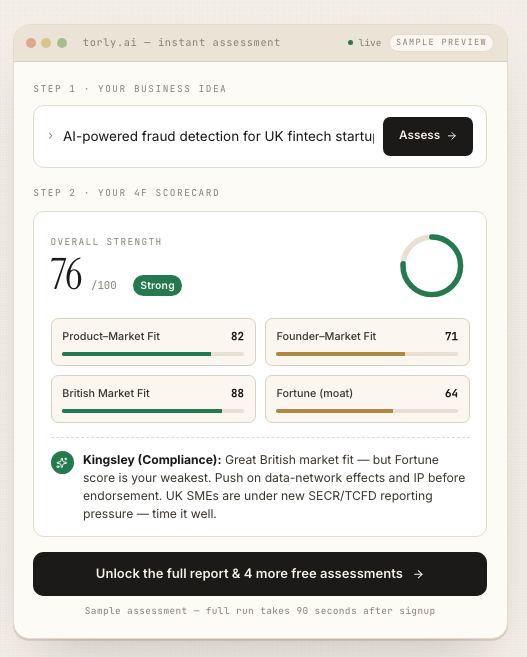
Creating sound financial projections visa assessors can actually get behind requires bridging the gap between innovative vision and cold, hard accounting logic. Many applicants spend months refining their pitch deck only to be rejected because their year-one customer acquisition cost appears miraculously low or their margin structure violates basic industry benchmarks. Rather than guessing your way through complex UK Home Office expectations, savvy founders are turning to the AI-Powered UK Innovator Visa Application Assistant to audit their metrics, stress-test their assumptions, and align their numbers with current endorsing body standards.
The Triad of Endorsement: Innovation, Viability, and Scalability
Endorsing bodies in the UK are bound by a strict mandate. They must verify three distinct criteria before granting a letter of endorsement: innovation, viability, and scalability. Most founders understand how to articulate innovation, but their financial tables fail to prove viability and scalability.
Viability means your business can survive on its own merits under realistic market conditions:
- Does your business plan account for statutory costs, UK salaries, National Insurance contributions, and Corporation Tax?
- Do you show realistic operational expenditures for hosting, security audits, and regulatory compliance?
- Can your working capital sustain the business before customer revenues ramp up?
Scalability means your model demonstrates genuine domestic and international growth potential without a linear explosion in headcount or operating cost:
- Are your customer lifetime value (LTV) calculations grounded in verifiable benchmarks?
- How does your gross margin evolve from Year 1 to Year 3?
- Can you prove genuine job creation targets for the resident labour market as required by the Home Office?
When you build out your forecast, every revenue stream must directly correlate with market size and customer acquisition channels. If your numbers show an immediate hockey-stick growth curve without corresponding marketing spend, evaluators will simply assume you do not understand the UK operating environment.
What Fintech Platforms Get Wrong About Cash Flow
Fintech ventures face unique operational hurdles that standard consumer apps never encounter. Building a financial model for a fintech platform means dealing with payment gateway reserves, currency volatility, merchant onboarding drag, and stringent regulatory fees.
Consider modern cross-border infrastructure tools like Airwallex. These platforms have demonstrated how software can simplify multi-currency accounts, international payouts, and embedded finance. They succeed globally because their backend infrastructure handles complex interchange fees, FX conversions, and compliance screening smoothly. If your startup aims to operate in or alongside this space, your financial model must reflect those same structural realities.
Many founders assume payment revenues arrive instantly at near-zero cost. In practice, international payment flows involve scheme fees, chargeback buffers, and regulatory capital requirements. If your financial forecast ignores these expenses, an endorsing body will spot the amateur assumptions instantly. You need a dedicated methodology that maps out every line item accurately before you submit your portfolio. You can TorlyAI BP Builder APP to generate structured financial plans that adhere to these specific sector benchmarks.
Structural Blueprint of a 3-Year Endorsement Model
An endorsement-ready model must contain several linked financial statements spanning a minimum of 36 months, with the first year broken down on a month-by-month basis.
1. The Revenue Build-Up Engine
Never plug flat revenue figures into your forecast. Endorsing bodies demand bottom-up modeling:
* Active paying users, average transaction volume, or subscription tier distributions.
* Churn rates that reflect standard industry attrition.
* Conversion rates based on real sales pipelines or proven digital acquisition funnels.
2. The Direct Cost & Gross Margin Model
Fintech platforms must document exact cost of goods sold (COGS):
* Cloud hosting infrastructure and security logging costs.
* Third-party API consumption charges (identity verification, AML checks, open banking connectors).
* Transaction processing fees and banking partner margins.
3. Operating Expenditure & UK Headcount Plan
The UK Innovator Founder Visa carries implicit expectations around economic contribution and job creation:
* Salaries must reflect current market compensation for engineers, compliance officers, and commercial staff in the UK.
* On-costs including workplace pension contributions and employer National Insurance must be mathematically linked.
* Professional fees for legal counsel, accounting, and annual audits must be factored in early.
If you are struggling to build these multi-layered sheets from scratch, you can Build your Business Plan NOW using intelligent systems configured specifically for UK visa guidelines.
Comparing Generic Templates with AI-Driven Validation
Many applicants try to cut corners by downloading generic startup financial templates from the internet. While these sheets look visually appealing, they are completely uncalibrated for immigration scrutiny.
Traditional spreadsheet templates treat your figures as passive data. If you enter an absurd assumption, such as doubling your revenue each month with zero marketing expenditure, a generic template simply calculates the total without warning you of the mistake.
In contrast, intelligent evaluation platforms act as active analytical agents. By comparing your proposed unit economics against historical success rates and Home Office criteria, automated evaluators highlight inconsistencies before an endorsing officer catches them.
Endorsing bodies will drill down into every calculation. If your target keyword research and financial assumptions fail basic stress testing, your application gets dismissed. Leveraging the UK Scale Up Visa AI gives you access to predictive insights that identify financial weak spots, ensuring your balance sheet, profit and loss, and cash flow forecasts stand up to deep scrutiny.
Balancing Founder Capital and Runway Preservation
One common question among applicants relates to minimum investment capital. While the strict £50,000 investment requirement of the legacy Innovator route was removed under the Innovator Founder rules, you must still prove you have sufficient funds to launch and sustain the venture until it reaches profitability.
Your financial model must clearly illustrate:
* Exact cash runway based on your available founding capital.
* The specific month your venture expects to achieve cash-flow break-even.
* A clear sensitivity analysis showing what happens if revenue is delayed by 3, 6, or 9 months.
If your projections show your business running out of cash in month seven without an articulated seed funding round or confirmed grant pipeline, your viability score drops to zero. Endorsing panels look for conservative, defensible projections. It is far better to showcase a steady, realistic pathway to profitability than an improbable, hyper-inflated valuation that falls apart under basic financial questioning.
To ensure your funding strategy matches current endorsing panel standards, you can Build Your Endorsement Application with 6 AI Agents that systematically review your cash burn rates and runway metrics.
Preparing for the Endorsement Body Interview
Submitting the numbers is only half the battle. Once your business plan passes initial screening, you will likely be invited to an endorsement interview. The panel will not just look at the totals; they will ask you to justify the assumptions behind the numbers.
Expect questions like:
* “Why did you project a 4% conversion rate when the B2B industry average is 1.5%?”
* “How do your Year 2 hiring plans support the job creation criteria for settlement?”
* “What is your fallback plan if user acquisition costs double in the UK market?”
If an external consultant wrote your plan, you will struggle to answer these questions organically. However, when you use agentic tools to develop your financial architecture interactively, you understand every formula, link, and assumption in depth. You can walk into your interview confident that your numbers are both operationally achievable and legally compliant.
Final Steps to Secure Your Visa Endorsement
Preparing an endorsement-ready financial blueprint requires diligence, financial literacy, and an up-to-date understanding of UK immigration policy. Do not leave your commercial viability to chance. Review your balance sheet, verify your compliance allowances, and ensure your operational roadmap matches your long-term scale-up strategy.
Take control of your immigration journey today. Equip your venture with precision modeling, eliminate structural blind spots, and present an undeniable commercial case by starting with AI-Powered UK Innovator Visa Application Assistant.