Digital Payment Solutions · October 12, 2026
Demystifying Digital Payment Platforms: How AI-Powered UK Innovator Visa Application Assistant Prepares Your Fintech Business Plan
Learn how AI-Powered UK Innovator Visa Application Assistant assists digital payment innovators in demonstrating British market viability to secure endorsing body approval.
The Fintech Frontier: Why Your Payment Innovation Needs Smarter Validation
Breaking into the UK fintech ecosystem is thrilling, yet setting up shop as an overseas founder brings serious regulatory friction. Digital payments are moving fast. Between cryptographic protocols for agentic commerce, embedded finance, and modern cross-border remittances, legacy architectures are crumbling. However, convincing an authorised endorsing body that your digital payment idea is genuinely novel, commercially viable, and scalable across Britain requires far more than generic slides. You must prove deep market alignment, rigorous regulatory understanding, and operational readiness. That is precisely where deploying modern AI Driven Visa Intelligence becomes the deciding factor between an outright rejection and a clear path to endorsement.
The journey demands that founders bridge complex technical architecture with strict Home Office immigration criteria. An endorsing body does not just want code repositories or speculative revenue projections; they want proof that you understand UK payment systems, consumer protection, and fraud mitigation frameworks. When you use an advanced AI platform to pressure-test your concept, you systematically eliminate blind spots before human evaluators ever lay eyes on your submission. By blending deep payment sector analytics with algorithmic compliance checks, overseas founders can now translate ambitious technical payment platforms into institutional-grade business plans tailored specifically for UK market expectations.
The Reality of the UK Innovator Founder Visa for Fintech Pioneers
Securing an Innovator Founder Visa is notoriously tough. You are judged on three distinct statutory pillars: innovation, viability, and scalability.
In the payments world, these three words carry unique weight:
- Innovation: You cannot simply build another white-label digital wallet. You must demonstrate genuine intellectual property, proprietary fraud logic, novel agentic shopping protocols, or ground-breaking ledger processing.
- Viability: Can you actually operate in Britain? Have you accounted for Financial Conduct Authority (FCA) authorisations, safeguarding rules, and initial share capital requirements?
- Scalability: Does your business model show a clear path to national employment creation, revenue expansion, and eventual export potential without stalling?
The UK receives thousands of enterprise visa applications annually, and endorsing bodies reject proposals that look like standard software agencies or repackaged domestic tools. The bar is exceedingly high. If you want to streamline this preparation, you can Build your Business Plan NOW using intelligent workspace tools designed directly around endorsing criteria.
Decoding Digital Payments: Agentic Commerce, Wallets, and Settlement Layers
The payments sector is experiencing a massive paradigm shift. We are moving from simple tap-to-pay apps toward autonomous agentic commerce. Consider recent industry milestones: autonomous digital agents browse e-commerce platforms, negotiate pricing, and execute transactions on behalf of users. Traditional risk engines often flag these AI interactions as malicious bots, prompting major card networks to engineer cryptographic protocols to authenticate non-human buyers.
If your fintech start-up touches this bleeding edge, your business plan must speak the language of modern financial infrastructure. Evaluators will question:
- How does your payment gateway differentiate between valid automated shoppers and malicious scraping scripts?
- What settlement latency do your merchant accounts experience during peak volumes?
- How do you comply with UK Strong Customer Authentication (SCA) while preserving frictionless user experiences?
Explaining these concepts in plain English, while backing them up with solid financial forecasting, is difficult. If your documentation misses these nuances, endorsing panels will question your technical leadership.
Common Pitfalls in Fintech Business Plans
Most rejected fintech plans fail for predictable reasons. Founders often focus entirely on the codebase while ignoring the regulatory reality of operating in London, Edinburgh, or Manchester.
Here are the standard errors that sink applications:
- Treating the UK market like any other territory. The UK payment rail structure (Bacs, CHAPS, Faster Payments) is mature and heavily regulated. Assuming your payment product can launch without clear licensing strategies is fatal to your application.
- Overestimating early adoption without validation. Endorsing bodies despise hand-wavy market sizing. They do not care about a multi-trillion-pound global market; they care about your serviceable addressable market within the UK SME or retail banking space.
- Ignoring compliance costs in financial projections. If your five-year profit and loss statement shows zero budget for AML/KYC checks, external audits, and legal counsel, evaluators immediately know you are unprepared.
To avoid these basic blunders, visionary founders harness TorlyAI BP Builder APP to audit their compliance budgets, test operational logic, and assemble bulletproof submission materials.
How Advanced AI Evaluates Your Payment Proposition
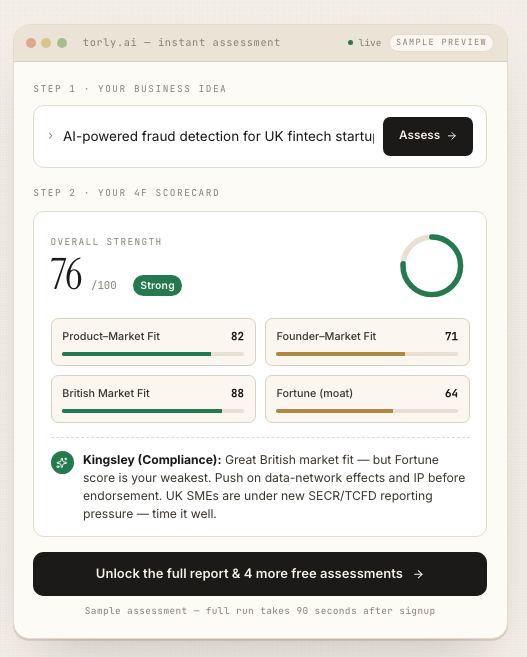
Human review processes can be unpredictable, but machine evaluations reveal systemic weaknesses in your narrative quickly. A specialist AI platform operates across three interconnected layers to prepare your fintech venture for scrutiny.
1. Business Idea Qualification
The algorithm examines whether your digital payments platform solves an authentic market problem. It compares your value proposition against existing UK competitors, testing if your feature set offers genuine innovation or mere cosmetic tweaks. It verifies whether your transaction fee economics, tokenisation stack, or wallet rails meet UK standards.
2. Founder Background Assessment
Endorsing bodies review your direct capacity to execute the project. The AI evaluates your professional track record, technical skills, and past commercial achievements, aligning them with the operational milestones laid out in your company roadmap.
3. Gap Identification and Strategic Roadmap
Rather than simply highlighting weak points, the system provides an actionable series of remediations. If your operational expenditure misses merchant acquisition costs, or if your compliance roadmap lacks specific mention of Payment Services Regulations, the platform isolates the deficit and guides your revisions.
Using targeted AI Driven Visa Intelligence provides an objective, 24/7 readiness check that gives founders the clarity needed to overhaul flawed assumptions before submitting documents.
Structuring the Ideal Innovator Founder Fintech Business Plan
Your written business plan must follow a clear, logical architecture. Here is how a successful fintech application should be organised:
- Executive Summary: A crisp overview of the payment problem, the unique technological solution, target market sectors, and capital requirements.
- The Problem Space: Concrete friction points in modern commerce, such as high cross-border acquiring fees, cart abandonment in agentic transactions, or settlement delays for British SMEs.
- Proprietary Innovation: A granular breakdown of your product architecture, security layers, API models, and machine learning components.
- Regulatory & Compliance Roadmap: Precise steps for interacting with the FCA, obtaining appropriate permissions (such as EMI or payment institution authorisation), and ensuring GDPR compliance.
- Market Analysis & Competitor Matrix: A realistic review of UK incumbents, identifying gaps where your platform commands a defendable edge.
- Marketing & Customer Acquisition: Direct strategies for onboarding merchants, payment orchestrators, or retail consumers.
- Five-Year Financial Model: Fully integrated cash flow, balance sheet, and profit and loss tables displaying sensible hiring plans and realistic revenue runways.
If you are starting from scratch or need to restructure your draft, you can Build your Business Plan NOW and follow guided frameworks designed to satisfy institutional assessors.
Step-by-Step: From Raw Payment Code to Endorsement Ready
To secure your endorsement without wasting months in revisions, follow this systematic workflow:
Begin by stress-testing your underlying value proposition against established UK market needs. Map out exactly how funds flow from consumer accounts to acquiring banks, ensuring that every intermediary is documented. Next, run your operational plan through multi-layered artificial intelligence platforms that audit your copy for logical inconsistencies, optimistic projections, or compliance oversights.
Once your core model survives algorithmic validation, finalise your dynamic five-year financial spreadsheets. Ensure your recruitment plan reflects true UK tech salaries, national insurance contributions, and commercial premises costs. Only then should you submit your dossier to an endorsing body for formal review.
Navigating the Endorsing Body Pitch
Securing an endorsement is not just a paperwork exercise; it often involves an interview or presentation before a panel of commercial assessors. These evaluators review dozens of pitches each week, so they spot rehearsed fluff instantly.
When presenting a digital payment concept, focus heavily on commercial realism:
- Demonstrate that you know who your initial ten enterprise customers or first 5,000 retail users will be.
- Articulate your unit economics down to the individual transaction basis points.
- Acknowledge systemic risks, such as card scheme rule updates or unexpected chargeback surges, and present ready-made mitigation plans.
Using structured platforms like TorlyAI BP Builder APP helps you anticipate aggressive panel questions, giving you clear answers grounded in verified commercial data.
Launching Your UK Fintech Journey with Confidence
The UK remains one of the world’s most dynamic environments for financial technology. From open banking protocols to pioneering agentic retail systems, the commercial opportunities for ambitious founders are massive. However, talent alone cannot bypass the legal and procedural requirements of the Innovator Founder Visa route.
Your business plan must stand as a masterclass in market viability, technological novelty, and regulatory awareness. By abandoning outdated consultancy methods and adopting intelligent, evaluation-driven software, you take complete control of your application narrative. You eliminate guesswork, shore up compliance gaps, and deliver an airtight proposal that commands respect from endorsing bodies.
Take the definitive step towards securing your endorsement by accessing leading-edge AI Driven Visa Intelligence to build, evaluate, and perfect your UK fintech business plan today.