Payment Security · October 5, 2026
FinTech Regulatory Standards: How AI-Powered UK Innovator Visa Application Assistant Validates Compliance
Learn how the AI-Powered UK Innovator Visa Application Assistant helps FinTech entrepreneurs validate complex regulatory standards and craft endorsement-ready business models seamlessly.
Navigating FinTech Red Tape: Why Endorsement Bodies Demand Ironclad Proof
Launching a financial technology start-up in the United Kingdom is brilliant, exciting, and frankly terrifying. You are building complex architecture, pitching to investors, and attempting to convince an endorsing body that your idea is genuinely innovative, viable, and scalable. But here is the hard truth: if your FinTech business plan glosses over payment security, anti-money laundering rules, or card data protocols, endorsing bodies will reject it immediately. Endorsement assessors do not just evaluate clean code or flashy UI; they want to know whether your platform will survive strict UK statutory frameworks. Making sure your venture ticks every regulatory box is where Visa Compliance Validation Software becomes indispensable for global founders aiming for a fast endorsement decision.
Many international entrepreneurs make the mistake of treating regulatory compliance as an afterthought, something to sort out after arriving in London. That approach fails every time. Endorsing bodies look for founders who understand the practical operational overheads of running a regulated business, from UK GDPR compliance to payment processing mandates. When you leverage an AI-Powered UK Innovator Visa Application Assistant, you can stress-test every operational claim before an assessor ever reads your proposal, turning legal and security hurdles into clear proof of your market readiness.
The Regulatory Labyrinth Facing FinTech Founders in the UK
The UK FinTech market is world-leading, but that prestige comes with serious gatekeeping. If your start-up handles card payments, moves funds, stores transaction records, or provides automated wealth advice, you operate under multiple layers of heavy scrutiny:
- Financial Conduct Authority (FCA) Authorisation: Determining whether your venture needs full authorisation, registration as an Authorised Payment Institution (API), or can operate as an appointed representative.
- Payment Card Industry Data Security Standard (PCI DSS): Strict rules governing anyone who accepts, processes, stores, or transmits debit and credit card details.
- UK GDPR & Data Protection Act 2018: Mandatory safeguards for personal financial data, cryptographic keys, and algorithmic profiling.
- Anti-Money Laundering (AML) and Know Your Customer (KYC): Statutory identity verification and transaction monitoring obligations under the Proceeds of Crime Act.
For an Innovator Founder Visa applicant, demonstrating awareness of these frameworks is not enough. You must show how your architecture handles them without draining all your seed capital.
Lessons from Payment Security: What PCI DSS Teaches Us About Visa Viability
Consider the Payment Card Industry Data Security Standard (PCI DSS). In corporate payment architectures, merchants and acquiring banks share the responsibility for protecting cardholder information. Solutions like ANZ Worldline, for example, demonstrate that maintaining security requires strict segmentation, annual self-assessment questionnaires (SAQs), secure point-of-sale environments, and rigorous network access controls.
Failure to follow these protocols results in severe fines, suspended processing privileges, and massive reputational damage. When UK endorsing bodies review your venture, they apply the exact same critical eye:
- Who owns the risk in your technology stack?
- Do you rely entirely on third-party APIs like Stripe or Adyen, or are you storing sensitive primary account numbers (PANs) on your own databases?
- If you are using cloud infrastructure, how is cardholder data isolated?
Answering these questions poorly signals to an endorsing body that your start-up is not viable. Conversely, mapping out your security controls explicitly proves that you are a serious operator who understands the commercial environment. To get these complex operational details into your pitch, you can use TorlyAI Desktop APP to draft structured, defensible operational strategies.
How AI Evaluates Business Viability Against Endorsement Body Standards
Immigration advisory firms often charge tens of thousands of pounds, yet many lack the technical depth to evaluate modern FinTech infrastructure. They might polish your grammar, but they rarely catch gaps in your payment security posture or regulatory roadmaps.
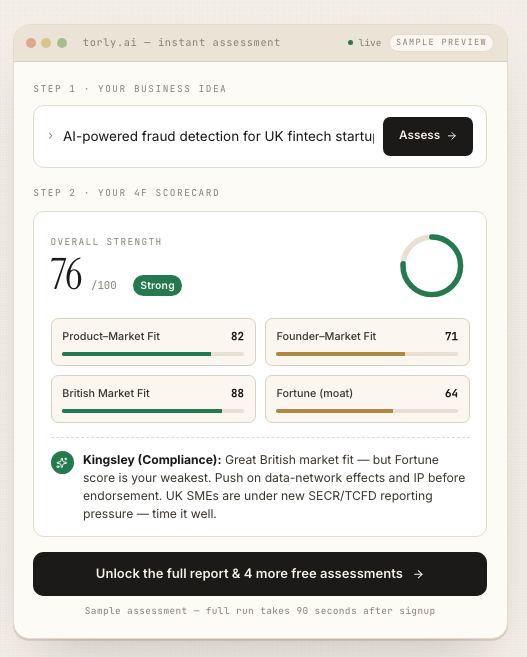
Modern AI reasoning agents bridge this gap by analysing your documentation across the exact pillars evaluated by UK Home Office endorsing bodies:
Torly.ai runs multi-layered assessments that mimic the rigorous evaluations conducted by official endorsing bodies. Its reasoning models read your technical narrative, cross-reference your architecture against UK regulatory obligations, and highlight blind spots. If you claim your app will launch in three months but your business model requires full FCA clearance that typically takes six to twelve months, the platform flags the contradiction before you submit.
When you configure your pitch through our dedicated Visa Compliance Validation Software, you ensure your timelines, compliance costs, and technical claims align seamlessly.
Common Compliance Traps that Derail FinTech Visa Applications
Why do so many technically sound FinTech concepts get turned down by endorsing bodies? It usually boils down to three avoidable mistakes:
1. Treating Third-Party Vendors as a Complete Legal Shield
Founders often write: “We use third-party APIs for payment processing, so we have zero compliance obligations.” This is false. Even when offloading payment processing, your platform still falls within the scope of PCI DSS compliance, requiring specific SAQ forms, safe token handling, and TLS encryption standards. Endorsing bodies spot this mistake immediately.
2. Ignoring Ongoing Audit and Maintenance Budgets
Assessing bodies scrutinise your financial run-rate. If your cash flow statements omit vulnerability scanning, regular penetration testing, data protection officer retainers, or annual validation costs, assessors will deem your commercial model unviable. You can map out these critical operational milestones using the TorlyAI BP Builder APP to ensure every line item makes financial sense.
3. Vague Data Sovereignty and Security Explanations
Simply stating that your data is stored “in the cloud” will not satisfy anyone. Assessors want to know if your database lives in UK or EEA data centres, how customer records are compartmentalised, and whether you comply with local banking secrecy requirements.
Bridging the Gap: From Rough Concept to Endorsement-Ready Platform
Preparing a visa application is fundamentally an exercise in risk mitigation. Endorsing bodies are tasked by the UK Home Office with finding founders who will build resilient, enduring businesses that generate domestic employment.
The process of de-risking your FinTech application involves distinct operational stages:
- Initial Qualification: Screening your raw idea against the Innovator Founder Visa criteria to confirm your solution is genuinely innovative rather than a basic clone of existing platforms.
- Founder Suitability Assessment: Matching your professional background, technical acumen, and leadership experience to the specific demands of your sector.
- Gap Analysis: Systematically discovering weaknesses in your commercial assumptions, whether that means unaddressed regulatory hurdles or unrealistic customer acquisition costs.
- Actionable Remediation: Reworking your operational blueprints, financial models, and governance frameworks to resolve those identified issues.
Instead of spending months trying to decipher Home Office guidance on your own, you can deploy takes you from idea to endorsement-ready business plan. 6 specialised agents. 31 skills. to accelerate your readiness.
Transforming Regulatory Demands into Your Strongest Pitch Asset
Regulatory friction does not have to be an obstacle in your application. In fact, tackling it head-on can be your greatest competitive advantage. When an endorsing body reads an application that lays out a concrete plan for security audits, data classification, and regulatory compliance, that application immediately stands out from the generic pitches crossing their desks.
By embedding continuous automated validation into your preparation, you eliminate guesswork, protect your capital, and present a bulletproof case to assessing bodies. If you are ready to prepare a robust application that meets the highest standards of the UK Home Office, take advantage of our comprehensive Visa Compliance Validation Software and take your FinTech concept from the drawing board to full UK endorsement.