Digital Currency and Blockchain · October 7, 2026
FinTech UK Innovator Roadmap: Navigating FCA Regulations with AI-Powered UK Innovator Visa Application Assistant
Learn how AI-Powered UK Innovator Visa Application Assistant guides Web3 and FinTech founders to align regulatory roadmaps with endorsing body innovation benchmarks.
Cracking the Code: The Realities of Endorsement for Web3 and FinTech
Building a disruptive financial technology venture in the United Kingdom is thrilling, but securing endorsement is notoriously tough. You are not just convincing a standard investor; you must satisfy strict Home Office benchmarks for innovation, viability, and scalability while respecting complex legal guidelines. If you are launching an onchain payment rail, stablecoin protocol, or digital asset custody solution, your product vision collides directly with the Financial Conduct Authority (FCA). Setting up a coherent UK Innovator Roadmap requires showing endorsing bodies that your technology is genuinely groundbreaking, legally bulletproof, and ready for market deployment.
Many technical founders fail not because their code lacks elegance, but because their regulatory and commercial roadmaps are disconnected. Endorsing bodies look for realistic milestones: how do you manage client fund segregation, maintain adequate share capital, and comply with anti-money laundering frameworks while capturing genuine market share? By working with an AI-Powered UK Innovator Visa Application Assistant, you can pinpoint critical governance blind spots, structure your narrative, and ensure your submission satisfies rigorous UK legal and compliance standards before an endorsing body panel even opens your file.
Why FinTech and Web3 Roadmaps Hit Walls with Endorsing Bodies
Endorsing bodies assess three core criteria: innovation, viability, and scalability. For an artificial intelligence or standard software company, viability often hinges on customer acquisition costs and technical validation. For FinTech, cryptoasset custody, and stablecoin platforms, viability is tied to regulatory clearance.
If an endorsing body suspects your business model requires permissions you have ignored, they reject the application. It is that simple. They will not endorse a startup that risks operating outside the law.
Here is where technical founders stumble:
- Treating Compliance as an Afterthought: Believing you can “build now, seek legal advice later” ruins endorsement prospects.
- Conflating Blockchain Novelty with Genuine Innovation: Deploying a standard ERC-20 token contract is not innovative in the eyes of an assessor. You must show proprietary architecture or unique market integration.
- Vague Operational Milestones: Projecting millions of pounds in transaction volume without accounting for capital adequacy requirements or custody safeguards.
- Weak Founder-Market Alignment: Failing to prove your technical background matches the heavy governance demands of modern financial platforms.
To bypass these hurdles, you must translate complex distributed systems into an airtight operational model. You can begin to Build your Business Plan NOW by breaking down compliance milestones, technical architectures, and user acquisition targets into a structure endorsing bodies respect.
Demystifying FCA Expectations: Stablecoins and Custody (CP25/14)
Recent regulatory developments, such as the FCA consultation paper CP25/14, highlight how the UK is formalising rules around fiat-backed stablecoin issuance and cryptoasset custody. If your startup touches digital asset settlement, these proposals directly dictate how you build your product roadmap.
The regulatory regime is shifting from simple anti-money laundering registration towards comprehensive conduct, consumer protection, and prudential oversight. Assessors expect you to understand these shifting sands.
Core Regulatory Realities for Web3 Innovators
- Reserve Asset Integrity: Stablecoin issuers must prove reserve assets are liquid, high-quality, and completely segregated. Assessor panels want to know your exact mechanism for guaranteeing continuous par-value redemption for users.
- Robust Custodial Segregation: If you provide wallet infrastructure or store user assets, your operational resilience must prevent co-mingling of corporate and client balances.
- Consumer Disclosures: Clear, accessible risk notifications are mandatory. If your platform targets retail users, the bar for compliance is dramatically higher.
- Operational Resilience: Technical failures, smart contract bugs, and downtime are treated as severe conduct breaches, not routine engineering hiccups.
When structuring your venture, showing you have anticipated these requirements turns regulatory hurdles into proof of viability. Demonstrating that your backend architecture accommodates these exact safeguards builds immediate credibility with endorsing bodies.
Designing a Bulletproof FinTech UK Innovator Roadmap
A viable UK Innovator Roadmap balances code deployment with legal progress. Assessors want to see realistic timelines, not wishful thinking.
Milestone 1: The Technical and Governance Prototype (Months 1–6)
Focus heavily on minimum viable product (MVP) development, cryptographic auditing, and formal legal preparation. You should establish your articles of association, identify which FCA permissions you will require, and run internal stress testing on private networks.
Milestone 2: Regulatory Sandboxes and Controlled Pilots (Months 6–12)
Move towards controlled testing environments. The UK provides world-leading regulatory sandboxes. Demonstrating plans to participate in an FCA testing cohort signals sophisticated planning to endorsing panels. During this phase, you validate your core value proposition using non-custodial or simulated capital flow.
To assemble documentation that reflects these precise benchmarks, consider deploying the TorlyAI BP Builder APP, which breaks your technical milestones into clear, endorsement-ready deliverables.
Milestone 3: Scale, Prudential Reserves, and Commercial Rollout (Months 12–24)
At this stage, you demonstrate active user acquisition, scalable infrastructure, and clear paths to profitability. Your roadmap must show sufficient cash runway, structured share capital, and transparent audit logging for onchain transactions.
By laying out your timeline this methodically, you assure the assessor that your business will survive the realities of operating in London or regional FinTech hubs. You can refine this using an intelligent UK Innovator Roadmap framework designed around official criteria.
Leveraging Multi-Agent AI to Secure Endorsement
Drafting documentation for an Innovator Founder Visa is time-consuming and fraught with pitfalls. Many founders spend months writing sprawling, unstructured plans that fail basic endorsement checks. This is why automated visa intelligence has become an essential asset for startup leaders.
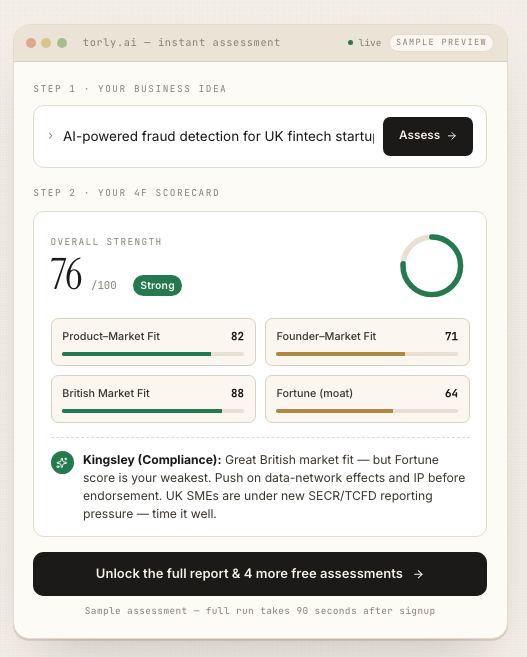
Torly.ai acts as an advanced readiness evaluation engine for entrepreneurs. Unlike basic generative text tools that write hollow marketing copy, Torly.ai runs multi-layered evaluations across your business concept and founder profile:
- Business Qualification Engine: It evaluates your FinTech model against Home Office rules for innovation, viability, and scalability. It checks whether your claims match real UK market gaps.
- Applicant Suitability Analysis: The platform reviews your professional history, verifying whether your background proves you have the skills to lead an FCA-facing technology company.
- Actionable Gap Identification: It flags operational weaknesses, regulatory risks, and structural flaws, giving you concrete action steps to fortify your proposal.
Instead of guessing what an endorsing assessor wants, founders gain access to an analytical workflow that mimics assessing panels. By running your pitch through an advanced engine, you can Build Your Endorsement Application with 6 AI Agents that review your market strategy, legal readiness, and technical roadmap concurrently.
Navigating Legal Nuances: Founder Advice
Working in the UK startup ecosystem is rewarding, but details matter. Here are practical pointers to bear in mind:
- Consult Licensed Professionals Early: An AI platform prepares your narrative, structures your strategy, and identifies gaps. However, for formal FCA filings or binding legal opinions, always consult an authorised UK solicitor.
- Keep Your Narrative Transparent: Endorsing panels do not expect you to have every full licence on day one. They expect honesty about what you have, what you need, and how much it will cost to obtain.
- Demonstrate UK Economic Contribution: Endorsing bodies love regional talent development. If your FinTech plans include hiring developers or operational staff across the UK, highlight that hiring plan in your wage budget.
- Track Home Office Changes: Immigration guidelines evolve constantly. Working with dynamic assessment software ensures your numbers match prevailing minimum requirements.
Preparing an endorsement application requires patience, precision, and an unshakeable strategy. If you want to systematically assess your concept, remove ambiguity, and prepare an ironclad submission, begin by refining your strategy through a purpose-built UK Innovator Roadmap.