FAQs · November 6, 2026
Innovator Founder Financial Projections FAQs: Expert Insights from Torly.ai
Find authoritative answers to critical financial projection questions for the UK Innovator Founder Visa, analysed and resolved by Torly.ai.
Cracking the Code on Innovator Founder Financial Projections
Let us be completely honest about endorsement applications. Most founders can pitch an exciting idea, build a sleek slide deck, and speak passionately about disruption. But when endorsing bodies like UK Endorsing Services (UKES), Envestors, or Innovator International open your financial model, the mood shifts immediately. Your numbers tell the unvarnished truth about whether your business can survive. Navigating Innovator Founder Financial Projections requires moving past back-of-the-napkin guesses and producing a mathematically sound, audit-ready forecast that proves commercial viability. If your cash flow runs dry in month eight or your margin assumptions look completely detached from UK market benchmarks, your application faces swift rejection.
Endorsing body panels see hundreds of business plans every month, and they spot inflated growth rates within thirty seconds. Building a credible financial model is not just about showing hockey-stick revenue; it is about proving that you understand unit economics, hiring timelines, operating expenditure, and tax obligations like VAT and National Insurance. If you want to bypass the guesswork and validate your financial readiness against real endorsing body criteria, check out the Innovator Founder Financial Projections evaluation engine on Torly.ai. In this guide, we break down the most urgent questions entrepreneurs ask when modelling their finances for UK endorsement, giving you clear answers grounded in Home Office expectations.
Why Do Endorsing Bodies Scrutinise Financial Plans So Heavily?
Endorsing bodies are tasked by the UK Home Office with assessing three statutory pillars: innovation, viability, and scalability. While innovation lives in your product narrative, viability and scalability live entirely inside your financial model.
Viability asks a blunt question: will this business stay solvent? Assessors look closely at your runway, break-even timeline, and working capital requirements. If your financial plan shows you running out of cash before revenue kicks in, you fail viability.
Scalability asks an equally tough question: can this venture create genuine economic impact in the UK? That means showing domestic job creation, export potential, and compound growth that outpaces traditional lifestyle businesses. Your financial model is the quantitative proof behind every single qualitative claim you make.
When preparing your submission, you can defending your business model: how AI-powered UK Innovator Visa application assistant prepares you for scrutiny to make sure your operational assumptions align with what panel reviewers expect to see.
Frequently Asked Questions: Financial Projections for Endorsement
1. How Many Years of Projections Must I Provide?
You must provide a comprehensive three-year financial forecast.
Year one should be broken down month-by-month. Endorsing bodies want granular visibility over your initial twelve months because that is where the execution risk is highest. Years two and three can be structured quarterly, though providing monthly breakdowns across all thirty-six months demonstrates superior operational planning.
Your model needs to present three foundational statements:
* A Profit and Loss Statement (P&L) showing turnover, cost of sales, gross profit, overheads, and EBITDA.
* A Cash Flow Forecast demonstrating actual cash movements, receipts, payments, and month-end bank balances.
* A Balance Sheet outlining assets, current liabilities, share capital, and retained earnings.
2. Do I Need Significant Investment Funds Upfront?
The legacy £50,000 minimum investment fund requirement was removed when the Innovator Founder route replaced the older Innovator Visa. However, this policy change creates a dangerous trap for unprepared applicants.
You still need sufficient capital to execute your business plan. If your forecast reveals that your software development, marketing, legal fees, and operational costs total £75,000 before you reach cash-flow positivity, you must demonstrate where that £75,000 will come from.
If you already possess personal savings or early angel funding, you must provide bank statements verifying available funds. If your plan depends on raising external capital later, you need a realistic, milestone-driven investment roadmap. Simply stating “we will raise £500,000 in seed investment” without showing investor pipelines, pitch schedules, or valuation rationales will lead to an immediate rejection on viability grounds.
To accelerate your preparation and generate models that match panel standards, you can Build your Business Plan NOW using desktop intelligence tools specifically built for the route.
3. What Are Common Financial Mistakes That Cause Rejections?
The most common error is the “hockey stick” curve supported by zero evidence. You know the graph: flat revenue for two months, followed by vertical growth that generates £5 million turnover by month twenty-four. Panels reject these fantasies instantly.
Here are the specific red flags assessors look for:
* Gross Margins Disconnected from Industry Norms: Claiming a 95% gross margin on a hardware-enabled service or physical product.
* Missing Staff Costs: Forgetting to budget for employer National Insurance contributions, workplace pension enrolment, or market-rate salaries.
* Zero Marketing Spend: Projecting thousands of paying users while budgeting £100 a month on customer acquisition.
* Confusing Turnover with Cash: Forecasting substantial billings while ignoring a 60-day invoice payment cycle, resulting in hidden cash-flow insolvency.
* Ignoring UK Tax Obligations: Omitting VAT registration implications or Corporation Tax provisions.
If you want an objective diagnostic to find these blind spots before you submit, testing your model with an AI-Powered UK Innovator Visa Application Assistant gives you real-time visibility into structural flaws that could trigger an endorsement refusal.

4. Can Co-Founders Share Financial Projections?
Yes, co-founders can apply together under a single business plan and unified financial model, provided both individuals meet the innovator criteria.
However, endorsing bodies evaluate each founder individually. Your financial plan must account for each founder’s role, operational deliverables, and financial remuneration. You cannot submit an identical plan where two co-founders take identical credit for the same commercial outputs without explaining equity division, executive responsibilities, and how capital supports both posts.
Furthermore, having two founders doubles your executive wage requirements, which naturally increases your early burn rate. Make sure your working capital forecast accounts for both directors drawing sufficient remuneration or holding documented personal maintenance funds.
5. What If My Venture Needs Further Investment Rounds?
Endorsing bodies welcome ambitious companies that require institutional venture funding. Needing capital down the line is not a negative; in fact, high-growth scalable ventures rarely self-fund past the seed stage.
The crucial requirement is explaining your capital strategy with precision. Rather than writing arbitrary funding targets into your cash flow, link each capital injection directly to operational milestones:
* Phase 1: Founder capital or angel syndicate funding (£60k) to finalise an MVP and acquire the first 100 pilot customers.
* Phase 2: Seed round (£350k) triggered at Month 14 once monthly recurring revenue hits £15,000, dedicated to hiring two UK software engineers and a business development lead.
* Phase 3: Series A (£1.5m) at Month 30 dedicated to international expansion.
Your financial model should display two scenarios: a baseline forecast assuming external funding arrives on schedule, and a conservative “downside” forecast showing how the business will control burn and survive if funding rounds take longer than planned. Reviewing UK Innovator Visa requirements explained by AI-Powered UK Innovator Visa Application Assistant can help clarify how statutory rules govern your future funding assumptions.
To make sure your financial documentation lines up across all compliance criteria, install the TorlyAI BP Builder APP and construct your application alongside specialized reasoning agents.
How to Structure Your Financial Assumptions Sheet
Every strong financial model starts with an explicit Assumptions Sheet. Assessors look at this tab before they inspect your P&L. If your assumptions are logical, they trust your projections. If your assumptions are absent, your entire model loses credibility.
| Financial Dimension | What Assessors Want to See | Critical Pitfall to Avoid |
|---|---|---|
| Customer Acquisition Cost (CAC) | Blended calculations across paid channels, content, and direct sales. | Assuming organic viral growth with zero marketing expenditure. |
| Lifetime Value (LTV) | Conservative churn estimates and defensible customer retention rates. | Projecting 100% renewal rates across a 36-month timeline. |
| Personnel & Hiring | Clear hiring milestones linked to revenue triggers, including UK PAYE. | Underpricing technical talent compared to average UK market salaries. |
| Direct Costs (COGS) | Hosting, payment processing fees (Stripe/PayPal), and customer support. | Treating gross revenue as net revenue without cost deductions. |
| Cash Reserves | Minimum buffer of three to six months of operating runway. | Allowing closing bank balances to drop into unbacked negative figures. |
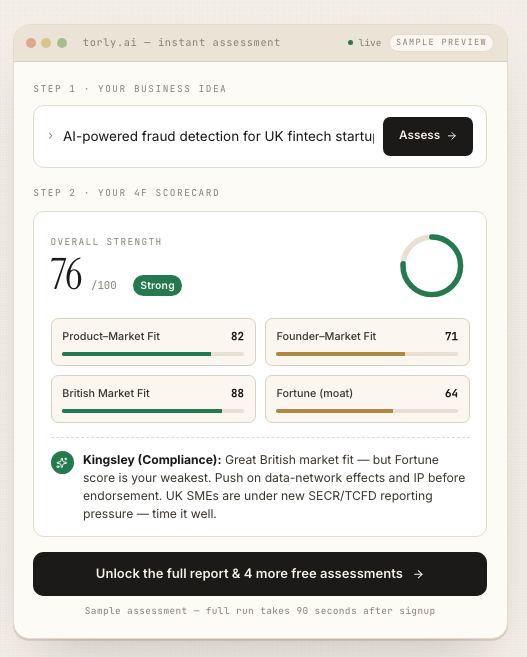
When your assumptions sheet clearly outlines the unit economics behind your business, panels can understand exactly how you plan to scale. You can also explore how structuring business viability for panels: Torly.ai 4F framework coaching helps organise complex operational models into coherent, high-conviction pitches.
Bridging the Gap Between Numbers and Interview Defence
Building an accurate spreadsheet is only half the battle. Once your business plan is shortlisted, you will face an endorsing body panel interview where assessors will test every single line item.
Can you explain your burn rate off the top of your head? Can you justify why your sales cycle takes 45 days instead of 90? Can you articulate what adjustments you will make if customer churn hits 8% instead of your projected 3%?
Assessors ask these questions to determine whether you are a real operator or someone reciting a plan written by a generic consultancy. Your operational instincts must match your numbers. If an assessor catches you hesitating over basic financial metrics like monthly cash burn or gross margin percentages, they will conclude that you lack the entrepreneurial capability required for the visa.
Take Control of Your Innovator Founder Financial Readiness
Preparing your financial projections does not have to be an overwhelming ordeal of broken spreadsheet formulas and immigration anxiety. By establishing realistic assumptions, budgeting accurately for UK operational realities, and proving your runway under multiple market conditions, you place your venture in the strongest possible position to earn an endorsement.
Torly.ai provides the advanced intelligence layer you need to pressure-test your plan. Through automated evaluation agents, multi-dimensional business plan analysis, and continuous compliance scoring, Torly.ai helps global founders eliminate blind spots and craft endorsement-ready documentation within 48 hours.
Take the guesswork out of your endorsement pathway and build a financial model that panels trust by exploring the complete Innovator Founder Financial Projections guidance platform today.