Financial Forecasting Guides · November 5, 2026
Mastering Startup Financial Forecasting with AI-Powered UK Innovator Visa Application Assistant
Discover how AI-Powered UK Innovator Visa Application Assistant automates robust three-year financial projections to satisfy strict endorsing body viability metrics effortlessly.
The Reality of Innovator Founder Financial Projections: Beyond Wishful Thinking
Securing an endorsement for the UK Innovator Founder Visa is one of the most rigorous hurdles any international entrepreneur will face. While many applicants spend weeks polishing product descriptions or refining tech architecture, applications routinely collapse in the finance section. Endorsing bodies do not care about wild guesses or hockey stick graphs that double revenue every month without justification. They want to see grounded, defensible, and methodically calculated Innovator Founder Financial Projections that prove your startup can survive the cold reality of the British commercial landscape. Meeting Home Office viability requirements means every single pound sterling listed in your operational costs and revenue pipeline must stem from demonstrable market logic.
To convince an assessing panel, you must present a three-year financial architecture that balances ambition with fiscal discipline. You need transparent cash flow models, defensible gross margins, realistic customer acquisition costs, and an unshakeable breakeven analysis. Navigating these requirements demands more than generic accounting templates; it requires dedicated tools designed around UK regulatory frameworks. By utilising specialised intelligence systems like the AI-Powered UK Innovator Visa Application Assistant from Torly.ai, prospective founders can model complex revenue streams, align balance sheets with Home Office viability rules, and eliminate the typical spreadsheet errors that trigger immediate endorsement rejections.
Why Endorsing Bodies Scrutinise Your Financial Projections
The UK Innovator Founder route is explicitly designed for high-potential, scalable ventures that bring tangible economic benefits to the United Kingdom. When reviewing your submission, endorsing bodies (such as Innovator International, Envestors, or UK Endorsement Services) act as gatekeepers. They evaluate your application across three core pillars: Innovation, Viability, and Scalability.
Your financial model is where viability and scalability collide. If your spreadsheet is fundamentally detached from commercial benchmarks, your innovation score will not save you.
Viability: Can the Business Actually Survive?
Viability asks a blunt question: Will this venture run out of capital before it achieves self-sustaining revenue? Endorsing bodies examine:
- Runway and Burn Rate: How long can the business operate on existing share capital, founder funds, or confirmed early investments before generating receipts?
- Working Capital Requirements: Have you accounted for delayed client receivables, VAT outlays, and stock staging?
- Realistic Overhead Projections: Have you budgeted for UK legal compliance, insurance, accounting, office space, payroll taxes, and software licensing?
If an endorsing body spots that you have budgeted £20,000 for full-stack developer salaries in central London, they know immediately that you do not understand the UK operating environment. That single oversight destroys your credibility.
Scalability: Can the Business Create Real Economic Value?
Scalability does not mean claiming you will capture 10% of a multi-billion-pound market by Month 18. Endorsement panels actively penalise lazy top-down calculations. Instead, they look for:
- Bottom-up unit economics showing sensible customer acquisition costs (CAC) against lifetime value (LTV).
- Evidence that margin efficiency improves as operational volume expands.
- Clear provisions for domestic job creation, demonstrating that your headcount growth tracks realistically alongside turnover milestones.
Preparing these interconnected metrics manually across a three-year timeline is daunting. If you want to streamline this complex modelling process, you can Build your Business Plan NOW using intelligent software agents that align your data with endorsing body expectations.
The Four Essential Pillars of a Three-Year UK Visa Financial Model
A complete, compliant financial projection for an endorsing body must cover three full years of trading. The first two years should ideally detail monthly performance, transitioning to quarterly or annual roll-ups for Year Three.
Let us examine each pillar in depth.
1. Granular Sales and Revenue Modelling
Your sales projection cannot rely on arbitrary lump sums. It must be broken down by:
- Product lines or subscription tiers.
- Sales volume, showing the precise count of units sold or active contract clients each month.
- Average revenue per user (ARPU) or average contract value (ACV).
- Churn rates that reflect real-world attrition.
Avoid the classic “hockey stick” curve. If your business shows flat revenue for six months followed by a sudden vertical jump to £100,000 a month with no corresponding surge in marketing expenditure or sales staff, evaluators will discard the submission. For a deeper look at aligning these operational milestones with your pitch narrative, check out our guide on structuring business viability for panels.
2. Comprehensive Expense Projections: Fixed vs Variable Costs
Every commercial venture operates on a split cost structure. Failing to properly distinguish fixed outlays from variable operating expenses shows a lack of financial literacy.
Fixed Expenses (Overheads):
These costs exist regardless of whether you have zero clients or a thousand. Your plan must budget for:
– Director compensation and UK employee payroll (including employer National Insurance contributions and workplace pensions).
– Professional fees (solicitors, chartered accountants, regulatory advisors).
– Office infrastructure, utility commitments, and digital tooling (server costs, security software, internal collaboration licenses).
Variable Expenses (Direct Costs):
Direct costs expand as sales climb. Evaluators look closely at your Cost of Goods Sold (COGS). For a software platform, this might mean server compute, payment gateway processing fees (e.g., Stripe’s 1.5% + 20p domestic rates), customer onboarding, and third-party API queries. For a hardware venture, it encompasses component procurement, warehousing, freight, and quality inspection.
3. Calculating the True Breakeven Horizon
Your breakeven point occurs when gross monthly revenue equalises total monthly expenditure, marking the transition to net operating profitability.
A common blunder among visa applicants is claiming the company will break even within three months of formation. Unless you are entering the UK with massive pre-signed enterprise contracts, instant profitability looks manufactured. Endorsing bodies understand that genuinely innovative tech ventures take eighteen to thirty months to achieve breakeven. They are far more impressed by a founder who demonstrates:
– A calculated, defendable cash dip (the “J-curve”).
– A clear understanding of maximum capital exposure (how much aggregate cash is consumed before reaching stability).
– A contingency buffer for delayed procurement cycles.
4. Cash Flow: The Metric That Decides Your Application
Net profit is an accounting abstraction; cash is concrete reality. Many startups fail on paper not because they lack market demand, but because their cash flow collapses. If you sell enterprise software on 90-day invoice terms, but must pay server bills and specialist contractors every 30 days, your cash flow is negative even if your P&L says you are profitable.
Endorsing bodies review your Cash Flow Statement to guarantee you have sufficient starting capital or secured grant commitments to fund that structural deficit until revenue collections match outgoings.
Benchmarking Your Numbers: Bottom-Up vs Top-Down Projections
To understand why so many applications fail review, compare how amateur applicants construct their spreadsheets against how professionals prepare an endorsement-ready package.
When evaluating applicants, endorsing officers immediately look for bottom-up validation. If you cannot explain the concrete mechanics behind how a prospect moves through your sales pipeline, your revenue numbers are fictional. To understand the wider framework required to navigate these expectations, read our breakdown of complete UK Innovator Founder Visa readiness.
How AI-Powered UK Innovator Visa Application Assistant Automates Compliance
Constructing dynamic, fully cross-referenced three-year financial projections by hand is time-consuming. A single formula error in an Excel workbook can cascade across your cash flow and balance sheet, leading an endorsing panel to question your analytical capabilities.
This is where dedicated agentic platforms transform the process. Rather than relying on static, generic financial templates, you can leverage the AI-Powered UK Innovator Visa Application Assistant to design, evaluate, and stress-test your financial forecasts in real time.
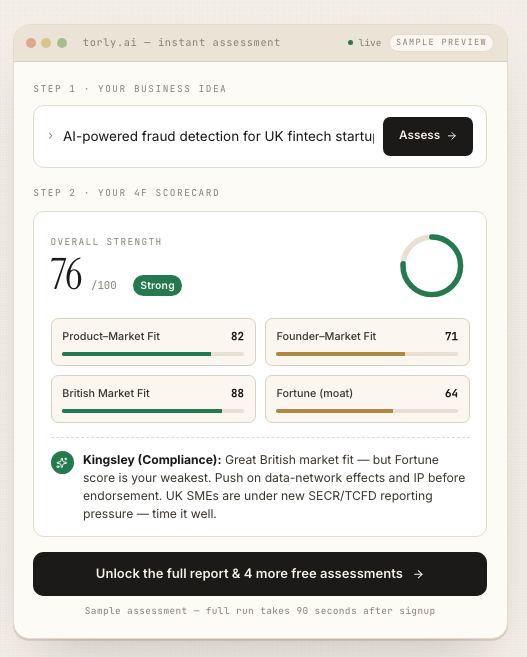
Powered by evaluation-driven reasoning engines, Torly.ai acts as an automated visa readiness analyst. It does not just aggregate data; it conducts multi-layered viability assessments tailored to the specific standards enforced by UK endorsing bodies:
- Dynamic Metric Validation: The platform evaluates your planned overheads against prevailing UK wage statistics, statutory obligations, and sector-specific operational benchmarks.
- Stress-Testing Engine: Torly.ai runs simulated sensitivity analyses, showing you what happens to your runway if client acquisition falls 20% below forecast, or if payment collection cycles lengthen by 45 days.
- Automated Documentation Alignment: It ensures that every numeric figure in your financial statements mirrors the assertions made in your operational plan, go-to-market strategy, and hiring milestones.
Entrepreneurs seeking an integrated path from raw business concepts to formal documentation can explore the TorlyAI BP Builder APP, which deploys six specialised AI agents and thirty-one discrete skills to prepare your application materials systematically.
Common Financial Traps That Derail Endorsement Decisions
Even seasoned founders frequently stumble over nuanced Home Office requirements when presenting their books to UK bodies. Watching out for these common traps can protect your application:
Trap 1: Underestimating British Payroll Taxes and Operational Overhead
Many international founders convert living costs or contractor rates directly from their home markets into pound sterling. This is an immediate red flag.
In the UK, employing staff involves substantial statutory overheads beyond headline gross salaries:
– Employer’s National Insurance: Standard rate of 13.8% on earnings above the secondary threshold.
– Workplace Pension Contributions: Mandatory minimum auto-enrolment contributions (typically 3% employer contribution).
– Apprenticeship Levy: Applicable if your wage bill exceeds specific national thresholds in later growth years.
Your financial model must capture these mandatory employer burdens alongside standard insurance policies, such as Public Liability and Employers’ Liability insurance (which is legally compulsory in the UK as soon as you hire staff).
Trap 2: Aggressive Sales Conversion Timelines
Assuming enterprise clients will sign five-figure annual contracts within thirty days of your company registration shows inexperience.
Enterprise B2B procurement in the UK regularly spans three to nine months. Your sales forecasts must incorporate:
– Formal procurement staging (discovery, vendor onboarding, security audits, legal review).
– Payment terms that respect UK standard commercial practices (typically Net 30 or Net 60 days).
– Realistic conversion funnels, accounting for the reality that only a minority of leads become paying clients.
Trap 3: The Missing Founder Subsistence Plan
Endorsing bodies will examine how you personally intend to survive while getting the business off the ground. Under the updated Innovator Founder Visa rules, the previous £50,000 minimum investment fund requirement was removed, but bodies still scrutinise subsistence.
If your financial plan shows zero founder salary for three years, the assessor will ask: How does this person pay their rent in the UK?
If you plan to live off personal savings, you must show clear bank documentation demonstrating sufficient personal maintenance funds. If you plan to draw a salary from the company, that wage must be factored directly into the business’s operational overheads and burn rate from day one.
Defending Your Projections During the Endorsement Interview
Submitting a flawless financial model on paper is only the first half of the challenge. Once your application passes initial desk review, you will face an endorsing body interview. During this panel assessment, reviewers will systematically test your assumptions.
They might ask:
– “Your model assumes a customer acquisition cost of £45. Walk us through the specific marketing channels and conversion rates that generate that figure.”
– “If your primary cloud hosting provider raises infrastructure fees by 25% in Year Two, how does that impact your gross margin and breakeven month?”
– “What is your cash buffer if your initial corporate pilot projects fail to convert into recurring contracts?”
If you stumble, give vague answers, or reveal that an external accountant drafted the numbers without your understanding, the panel will issue a rejection. You must know your financial model inside and out. To prepare for these aggressive panel questions, review our complete walkthrough on how to defend your business model under scrutiny.
Action Plan: Steps to Build Endorsement-Ready Projections
Follow this phased approach to draft your three-year financial forecast:
Step 1: Establish Your Core Baseline Costs
Catalogue every non-negotiable expense required to keep the company legally compliant in the UK. Include Companies House filing fees, registered office address services, corporate banking charges, and basic accounting provisions.
Step 2: Define Realistic Unit Economics
Calculate your Gross Margin per unit or per client engagement. Clearly isolate your direct costs from your gross profit so assessing officers can see that your venture achieves operational leverage as volume grows.
Step 3: Map Your Monthly Cash Runway
Build a 24-month detailed cash ledger before aggregating Year Three into quarters. Ensure that at no point does your closing cash balance hit zero. Incorporate a reasonable safety margin to absorb delayed invoice payments.
Step 4: Stress-Test Your Forecasts
Prepare three distinct scenarios: Conservative, Base, and Aggressive. Endorsing bodies appreciate founders who present a grounded Base case while having a clear contingency plan if market traction aligns with the Conservative projection.
Step 5: Audit for Endorsement Alignment
Before submitting your application, conduct a thorough cross-check between your financial workbook and your narrative business plan. Every marketing initiative described in your text must have a matching line item in your expense budget; every service launch must mirror the revenue timeline.
Conclusion: Transform Financial Uncertainty into Endorsement Confidence
Your financial model is not an administrative afterthought; it is the commercial engine that proves your venture is viable, credible, and worthy of endorsement. Endorsing bodies are tasked with filtering out unfeasible propositions, and an incomplete, unverified, or top-down financial model is the fastest route to a refusal.
By building your forecasts around transparent UK operational data, defensible bottom-up sales mechanics, and strict cash flow discipline, you present yourself not just as an ambitious inventor, but as an accomplished, capable business leader.
Do not leave your immigration journey and commercial aspirations to chance. Take command of your viability metrics, eliminate spreadsheet guesswork, and secure your future by leveraging the AI-Powered UK Innovator Visa Application Assistant to craft rigorous, panel-ready financial projections today.