Financial Services Overview · September 25, 2026
Navigating Financial Viability: How Torly.ai Validates Your UK Innovator Founder Capital
Explore how Torly.ai provides structured financial readiness assessments and compliance checks that traditional financial institutions cannot offer for UK visas.
The Harsh Reality of UK Visa Finances: Why Banks Fall Short
Securing endorsement for a UK Innovator Founder Visa is notoriously tricky, especially when you hit the financial section. Most international founders assume that showing a healthy personal bank balance or bringing corporate statements from traditional financial institutions is enough to clear the bar. In reality, traditional corporate institutions like SWBC focus strictly on conventional commercial risk, personal credit lines, and legacy lending metrics. They know how to manage asset-backed loans and employee benefits, but they have zero understanding of what an approved UK endorsing body looks for in an early-stage startup cash flow model.
When endorsing bodies scrutinise your application, they are not asking if you can service a mortgage; they want to know whether your capital is genuinely viable, properly allocated, and legally compliant with strict Home Office regulations. This is precisely where modern automation steps in. By leveraging a specialised Visa Application Autopilot, founders can run multi-layered compliance checks, stress-test their runway, and structure their financial evidence to match exact immigration benchmarks before submitting a single document.
The Great Disconnect: Traditional Banking vs Endorsement Realities
Why do standard financial services fail startup visa applicants? It comes down to intent.
Mainstream financial institutions, from multinational banks to diversified service platforms like SWBC, are built around established risk models. They handle:
* Institutional risk mitigation
* Vehicle loan tracking and mortgage servicing
* Standard payroll management and commercial insurance
These services protect capital in predictable, established domestic environments.
However, UK endorsing bodies operate under completely different criteria. They do not care about your personal credit score in another country. Instead, they examine your venture through three distinct lenses: innovation, viability, and scalability.
A traditional bank statement will never explain how your seed capital covers customer acquisition costs over an 18-month runway. Nor does a loan approval letter prove that your funds are free to spend in the UK startup ecosystem without third-party encumbrances. When founders rely solely on ordinary bank letters, they often receive immediate rejections due to vague spending breakdowns, unverified sources of funds, or unrealistic financial projections.
To bridge this gap, founders need tailored tooling that understands immigration law as well as venture finance. Using the TorlyAI Desktop APP gives founders an immediate operational advantage, turning abstract numbers into an audit-ready financial proposal that endorsing bodies respect.
Deconstructing the Innovator Founder Capital Standards
Let us break down what the UK Home Office and endorsing bodies actually demand from your balance sheet.
1. Proof of Source and Legal Transfer
You cannot simply drop funds into an offshore account and call it working capital. Endorsing bodies demand an immaculate paper trail showing the exact legal origin of every pound. Whether it stems from personal savings, angel investment, or venture capital, the funds must be cleanly auditable and legally transferable to the UK.
2. Viability and Burn Rate Alignment
Your capital must match your milestones. If your pitch claims you will build a proprietary machine learning engine within six months, but your financial plan only allocates £800 a month to engineering salaries, your application will fail the viability test. Endorsing bodies compare your budget line by line against current UK market salaries, software licences, legal fees, and operational overheads.
3. Scalability-Driven Cash Reserves
It is not enough to survive year one. Endorsing bodies want evidence that your capital can sustain scaling activities into years two and three. They look closely at your unit economics:
* Gross margins
* Customer acquisition cost (CAC)
* Lifetime value (LTV)
* Projected headcount expansions
If these figures are not grounded in real market data, your business plan will be flagged as purely theoretical.
How Intelligent Automation Validates Founder Readiness
Navigating these intricacies manually takes months of trial, error, and expensive legal consultations. That is why smart entrepreneurs use intelligent platforms designed to handle the heavy lifting.
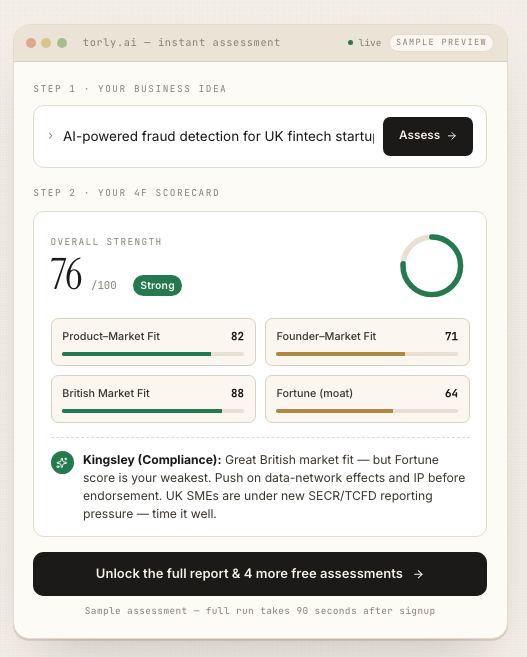
Torly.ai acts as an intelligent visa readiness analyst, deploying advanced reasoning agents that stress-test your financials in real time. Rather than treating your balance sheet like a passive document, the platform runs active simulations to see how your runway holds up under shifting regulatory expectations.
By setting up a reliable Visa Application Autopilot, you remove guesswork from your financial statements, identifying red flags in your burn rate long before an endorsing officer spots them.
The system evaluates:
* Capital sufficiency: Does your declared funding truly support your product roadmap?
* Allocation realism: Are operational expenditures distributed in line with UK industry benchmarks?
* Home Office compliance: Does your documentation satisfy the evidentiary thresholds demanded by UK immigration rules?
If you want to move quickly from a raw concept to an investor-grade forecast, you can Build your Business Plan NOW using automated tools built specifically for visa compliance.
Comparing the Two Worlds: Traditional Finance vs AI Visa Intelligence
| Financial Dimension | Traditional Institutional Approach (e.g., SWBC style) | Torly.ai Agentic Platform |
|---|---|---|
| Primary Focus | Debt servicing, insurance protection, and credit risk | Startup viability, innovation, and visa rule adherence |
| Regulatory Scope | Domestic commercial law and banking standards | UK Home Office immigration rules and endorsing guidelines |
| Runway Analysis | Historic cash flow and personal balance reviews | Forward-looking burn rate vs development milestones |
| Turnaround Speed | Weeks of manual human underwriting | Instant, 24/7 algorithmic review and dynamic scoring |
| Strategic Feedback | Binary pass/fail decisions on loan applications | Detailed gap analysis and actionable improvement roadmaps |
Traditional institutions are great at running conventional business operations, but they simply do not speak the dialect of UK visa endorsement. Relying on them for immigration readiness is like using a road atlas to navigate ocean currents; the context is entirely wrong.
Turning Financial Gaps into Strategic Strengths
One of the greatest hazards in preparing an application is the blind spot. Founders often believe their numbers are solid, simply because their spreadsheets balance. But an endorsement panel looks deeper:
- Does the marketing budget make sense for the chosen target geography?
- Is there adequate working capital reserved for unexpected regulatory delays?
- Does the founder have enough personal maintenance funds separate from the business capital?
Torly.ai does not just point out errors; it generates a concrete gap identification and action roadmap. If your projected tech spend is too low, the platform flags the deficiency and suggests realistic ranges based on actual UK operational benchmarks. If your hiring timeline is overly ambitious for your seed reserve, the AI restructures your hiring roadmap to preserve cash flow.
You can streamline this entire process by choosing to Build Your Endorsement Application with 6 AI Agents, ensuring that every commercial claim in your plan is supported by your financial schedules.
Step-by-Step: Preparing Your Capital Evidence for Submission
If you are gearing up to submit your endorsement pack, follow these actionable steps to ensure your capital stands up to scrutiny:
- Segregate Your Capital Accounts: Keep your personal maintenance funds completely separate from your business operational funds. Mixing them is a guaranteed way to raise doubts during evaluation.
- Document the Audit Trail: Collect original bank letters, dividend vouchers, or verified investment agreements showing the exact origin of your funds.
- Map Every Pound to a Milestone: Never list broad, round numbers under vague headings like “Operations: £50,000”. Break it down into cloud hosting, talent acquisition, legal fees, accounting, and compliance.
- Stress-Test Your Runway: Run dynamic scenarios where your customer acquisition costs double or your sales cycle slows by three months. Ensure your venture survives without needing an immediate emergency injection of cash.
- Run Algorithmic Compliance Checks: Before spending thousands on legal submission fees, validate your pack through automated readiness scoring.
The Verdict: Secure Your Founder Route with Precision
The UK Innovator Founder Visa offers an incredible path for forward-thinking entrepreneurs ready to build transformative companies in Britain. However, the regulatory barrier to entry has never been higher. Endorsing bodies have zero tolerance for sloppy financial planning, unsupported balance sheets, or unrealistic market projections.
Traditional commercial financial platforms provide valuable daily tools for existing businesses, but they are not equipped to prepare your immigration strategy. To clear the endorsement bar on your first attempt, you need targeted intelligence that evaluates your profile against the real rules of the game.
Take control of your submission today. Deploy a dedicated Visa Application Autopilot to audit your financial viability, eliminate documentation gaps, and build an endorsement-ready case that opens the door to your UK expansion.