Banking Services · November 3, 2026
Setting Up UK Business Banking: AI-Powered UK Innovator Visa Application Assistant Financial Tools
Master your startup banking and Home Office financial prerequisites using AI-Powered UK Innovator Visa Application Assistant to build robust financial models.
Cracking the UK Business Banking Maze for Visa Endorsement
Setting up a commercial bank account in the United Kingdom sounds straightforward until you try doing it as a visa applicant. When you apply for the UK Innovator Founder Visa, the Home Office and endorsing bodies expect your financial house to be completely in order. It is not just about having money sitting in an account overseas; you need to demonstrate realistic financial projections, understand operating expenditure, and prepare for statutory cash flow reporting under British regulatory standards. Getting these numbers wrong can derail your entire endorsement, making early financial preparation a absolute priority for any ambitious international founder.
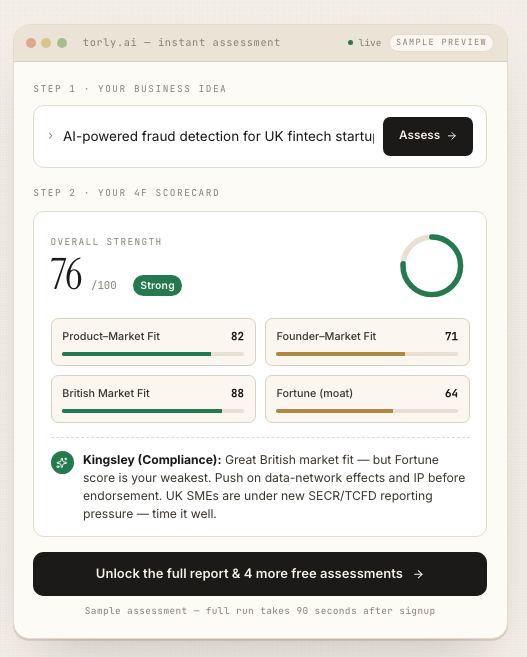
Navigating this terrain requires robust proof that your venture is financially viable and completely compliant with domestic financial frameworks. By utilising Entrepreneur Visa Verification through Torly.ai, you can assess whether your commercial figures hold up against strict endorsing body expectations before you ever approach a bank manager or submit a portfolio. Securing your business banking setup and passing immigration scrutiny are two sides of the same coin: you must show that your capital is genuine, your burn rate is calculated, and your UK startup is structured for sustained market growth.
Why British Business Banking Catches Global Founders Off Guard
Opening a business bank account in Britain is notoriously bureaucratic for non-residents. High street institutions like Barclays, HSBC, NatWest, and Lloyds enforce rigorous Know Your Customer (KYC) and Anti-Money Laundering (AML) standards. They want proof of a UK operating address, verified director identities, Companies House registration details, and clear explanations of where every single pound originated.
For an early-stage founder moving across borders, this creates a classic chicken-and-egg problem:
* You cannot easily open a traditional UK corporate account without an active visa and a registered UK address.
* You cannot easily secure endorsement without demonstrating that your startup has immediate access to sufficient investment capital or clear pathways to bank operational funds in the UK.
* Endorsing bodies evaluate your 3-year cash flow forecast, your pricing models, and your planned working capital before granting an endorsement letter.
Traditional commercial checking accounts, such as basic entry-level business accounts offered by high street players or institutions like PNC overseas, are built for low-volume daily operations, routine deposits, and basic card spending. They are great for buying office supplies or paying software subscriptions, but they do nothing to validate your financial viability under immigration rules. An entry-level checking facility provides a basic repository; it does not build your visa case. You need financial documentation that proves market feasibility, unit economics, and capital sufficiency.
To make sure your financial narrative matches the strict criteria of endorsing panels, you must look beyond basic banking checklists. Before you step in front of evaluators, reading up on structuring business viability for panels: Torly.ai 4F framework coaching can help you structure your numbers around market reality rather than speculative wishful thinking.
The Home Office Financial Thresholds You Cannot Afford to Ignore
When the UK government revised the startup visa landscape into the unified Innovator Founder Visa, they removed the strict £50,000 minimum investment capital rule for every applicant. That sounded like fantastic news on paper. In reality, it shifted the burden of proof directly onto the founder’s shoulders.
Today, you must prove that your business idea is:
1. Innovative: Genuinely original and solving a verified market problem.
2. Viable: Financially sustainable with realistic forecasts and clear revenue models.
3. Scalable: Showing potential for significant job creation and growth across the UK market.
Endorsing bodies will dissect your financial projections to see if your venture will run out of money in month six. They look at your monthly burn rate, customer acquisition costs (CAC), lifetime value (LTV), and payroll requirements. If your financial model assumes hiring three senior software engineers in central London on £25,000 per year, your application will be rejected on viability grounds instantly.
To make sure every metric aligns with what caseworkers expect, you can install the Build your Business Plan NOW suite, which structures your financial assumptions into an endorsement-ready format that leaves zero room for ambiguity.
Traditional Bank Accounts vs AI-Driven Financial Readiness
Many entrepreneurs assume that walking into a bank with an impressive balance sheet is enough. It is not. Traditional banks care about risk mitigation and account fees; they do not care whether your enterprise meets paragraph 24A of the immigration rules.
Here is how basic commercial banking stacks up against dedicated visa intelligence tools:
| Feature / Requirement | Entry-Level Business Bank Checking | Dedicated Innovator Visa AI Financial Tools |
|---|---|---|
| Primary Purpose | Daily cash handling and bill payments | Demonstrating viability, innovation, and scalability |
| Visa Compliance Checks | None (purely financial compliance) | Automated validation against endorsing body criteria |
| Projections & Modelling | Basic cash flow insights and transaction logs | Dynamic 3 to 5-year multi-scenario financial forecasts |
| Proof of Funds Evaluation | Simple balance verification statements | Origin-of-funds verification and runway analysis |
| Turnaround Speed | 3 to 8 weeks for non-resident directors | Instant continuous evaluation with rapid turnaround |
While a basic checking account gives you a debit card and online bill payments, an AI-powered assistant works as an active visa readiness analyst. It identifies structural gaps in your unit economics, points out unfeasible expenditure assumptions, and prepares you for the detailed interrogation you will face from assessment committees.
When you need an objective assessment of your startup’s financial readiness, using the Entrepreneur Visa Verification engine ensures your business plan does not crumble when scrutinised by forensic assessors.
Step-by-Step Guide: Establishing Your UK Startup Financial Base
Setting up your UK operations smoothly requires tackling the paperwork, legalities, and banking steps in a clear sequence. Do not rush out to apply for accounts before completing the underlying groundwork.
1. Register with Companies House
Your UK legal entity must be formed first. Ensure your memorandum of association, articles of association, and share capital structure are clear. Keep your cap table simple: complex offshore holding structures often trigger lengthy banking compliance investigations.
2. Choose Between High-Street and Modern FinTech Accounts
For initial operating capital, many international founders start with UK-regulated electronic money institutions (EMIs) such as Wise Business, Revolut Business, or Tide. These platforms offer rapid onboarding for cross-border teams while you await your biometric residence permit. Once your visa is granted and you possess a domestic residential address, establishing an account with a traditional clearing bank becomes significantly easier.
3. Maintain Complete Transparency Regarding Capital Sources
If you are funding the business with personal savings, family contributions, or third-party angel investment, compile a pristine audit trail. Endorsing bodies and banks alike will inspect bank statements covering at least three to six months. Unexplained lump sums are an immediate red flag.
4. Build a Robust Operational Budget
Your budget must reflect realistic UK costs:
* Office or co-working space rental.
* National Insurance contributions and statutory pensions for UK employees.
* Value Added Tax (VAT) registration thresholds and reporting deadlines.
* Legal, accounting, and regulatory compliance fees.
To familiarise yourself with the foundational rules that dictate these assessments, take a look at our breakdown on UK innovator visa requirements explained by AI-Powered UK Innovator Visa Application Assistant.
Overcoming Common Banking and Endorsement Pitfalls
Navigating UK compliance often feels like walking through a minefield. Here are the recurring stumbling blocks international founders face and how to bypass them:
Misjudging the Cost of UK Talent
A frequent mistake made by overseas applicants is underestimating London and regional wage rates. If your tech startup relies on machine learning engineers or senior product managers, your financial plans must reflect realistic market salaries. Submitting deflated payroll figures makes your venture look unviable to an experienced endorsing body panel.
Relying on Generic Financial Templates
Using generic software templates often produces disconnected revenue forecasts. Assessors review hundreds of business plans every quarter; they immediately spot generic revenue models that show hockey-stick growth without corresponding marketing expenditure. Your numbers must reflect a direct connection between customer acquisition spend and sales conversion.
When formulating your underlying strategy, reviewing smart tools for endorsement: AI-Powered UK Innovator Visa Application Assistant will help you avoid generic pitfalls and refine your strategic positioning.
If you want to eliminate guesswork entirely, you can deploy the specialised TorlyAI BP Builder APP to produce calibrated financial narratives that align perfectly with endorsing standards.
Leveraging AI to Secure Financial Validation
Building a commercially viable startup while navigating British immigration rules is tough. Between managing international transfers, understanding UK tax liabilities, and satisfying endorsing panel checklists, you cannot afford to waste weeks on guesswork.
Modern intelligence platforms bridge this gap by simulating the exact scrutiny your application will undergo. Rather than waiting for a rejection letter to discover a flaw in your financial viability calculations, you can pressure-test your assumptions beforehand. By running multi-layered checks across your business idea, your professional background, and your commercial forecasts, you gain total clarity on where your file stands.
Ready to confirm your startup meets every Home Office and endorsing body benchmark? Rely on Entrepreneur Visa Verification with Torly.ai to refine your financials, eliminate application blind spots, and take your UK entrepreneurial journey forward with confidence.